Everpeak Properties
العقاراتحاسبة الاستثماراستشارة خاصة · من مليون يورو
EVERPEAK INVESTMENT

عقارات للاستثمار.

قارن أسعار الشراء وبيانات الإيجار المتاحة والعائد الإجمالي. استكشف العقار واحسب نتيجتك الشهرية.

EVERPEAK · DEVELOPMENT

Development projects

Five projects with reviewed source documents and separate scenario economics. Actual purchase prices are on request. All purchase prices, budgets and exit values below are illustrative assumptions.

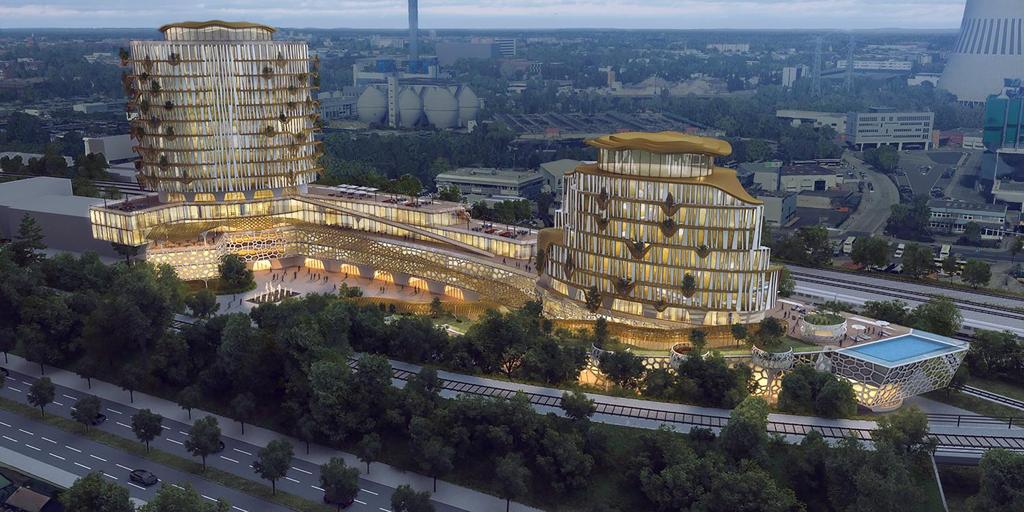
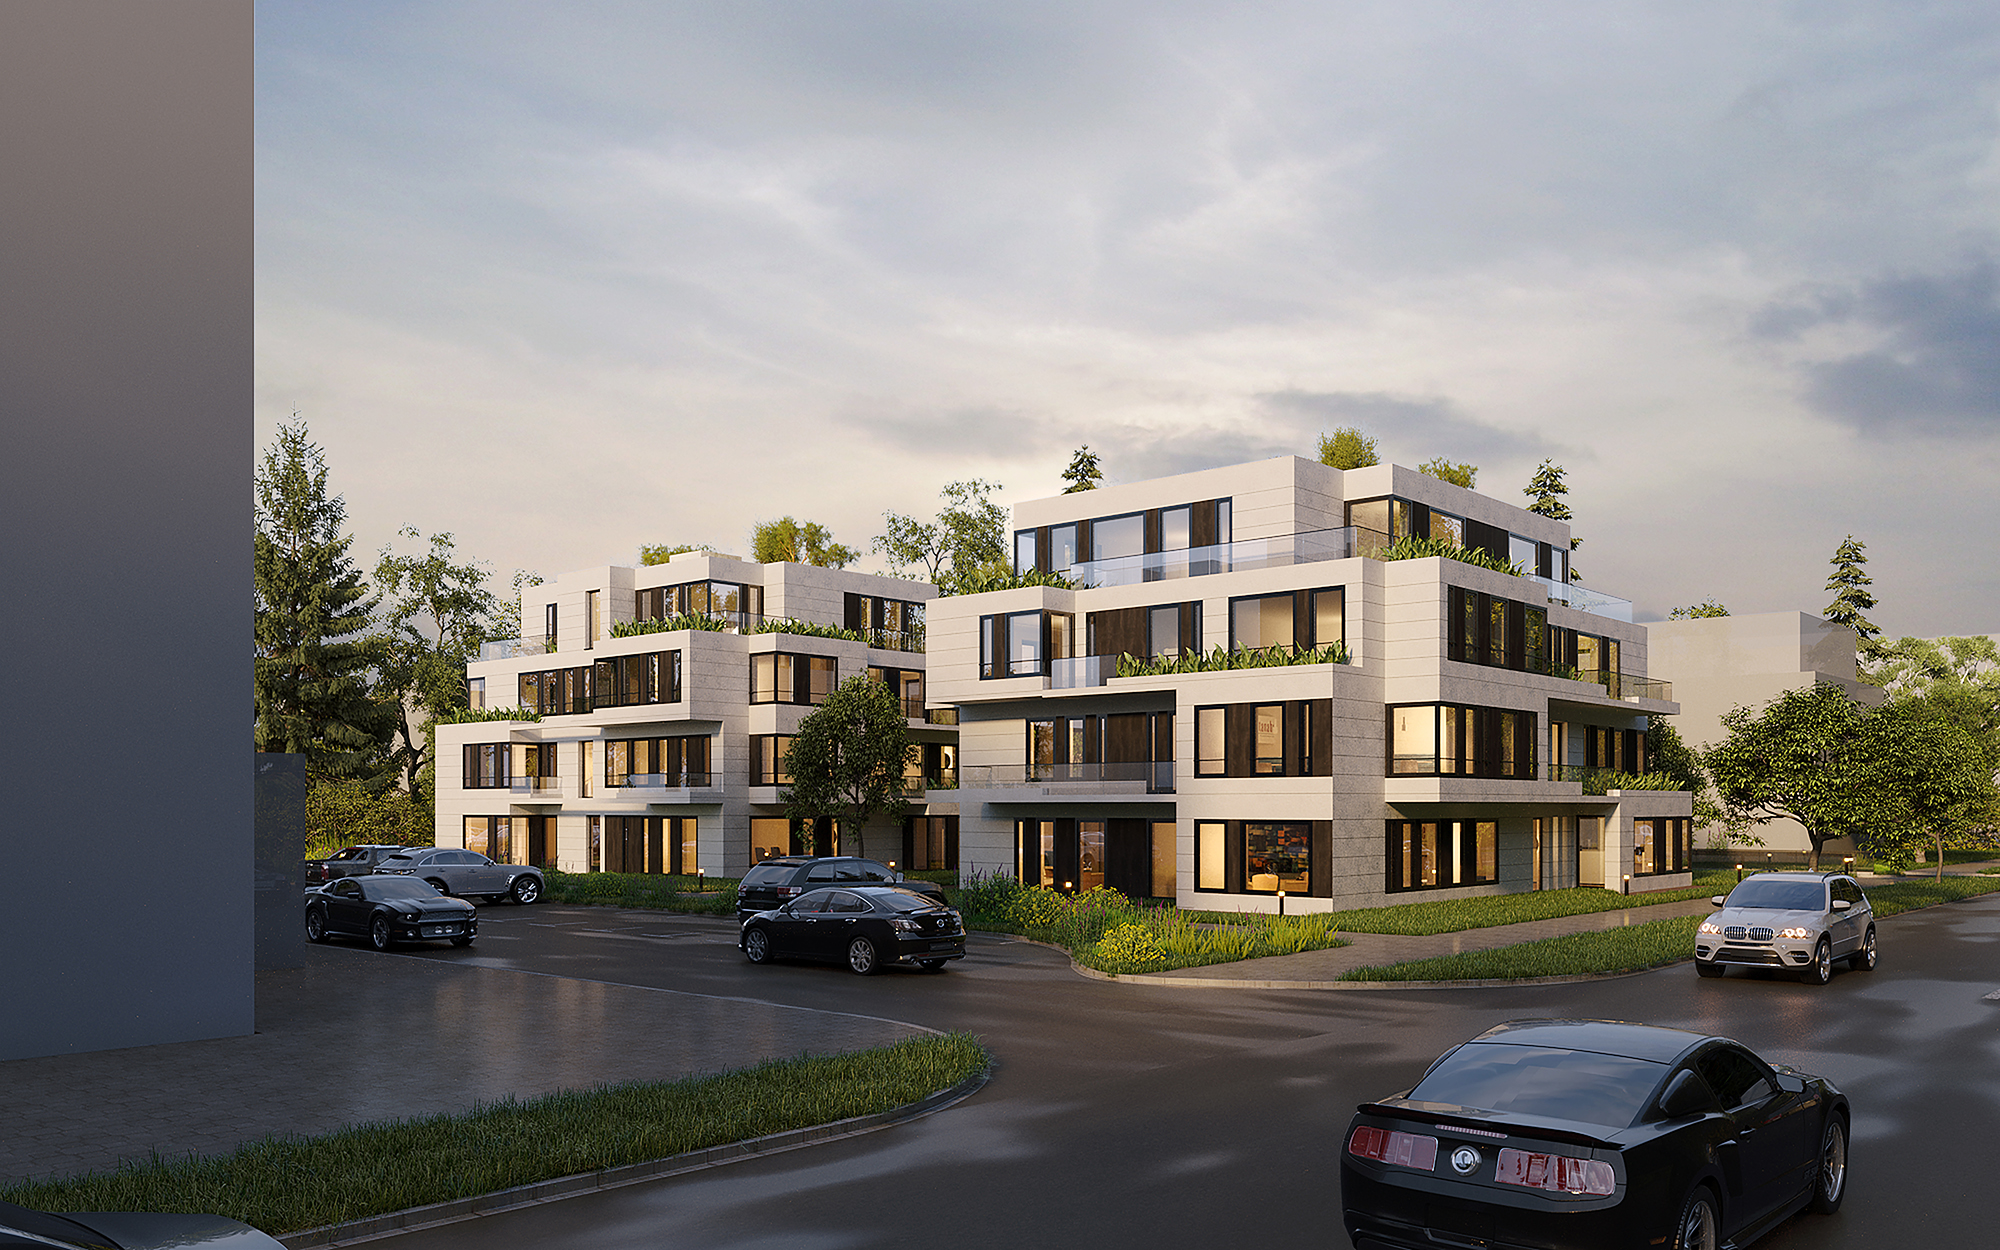
Klärwerkstraße 1 / 1A

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Klärwerkstraße 1 / 1A

Actual purchase price on request

Open presentation ↗

Project link ↗

Commercial development potential based on a 2020 study; railway-purpose release and contaminated-land investigations remain unresolved.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-27.41 %-27,762,387 €
Base-3.55 %-3,188,355 €
Upside10.92 %9,370,202 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost89,699,284 €
Net exit proceeds86,510,928 €
Project profit / loss-3,188,355 €
ROI over the whole project-3.55 %
Illustrative annualized return-0.72 %
Gross proceeds needed to break even92,473,488 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Uses only Real Case 31,852.33 m² BGF, not the larger theoretical concepts. Hard costs: BGF × €1,900/m². Assumed saleable floor area: 80% of BGF × €3,500/m². Neither the efficiency ratio nor exit price is verified.
  • €4m extra-works allowance for investigations, remediation/site preparation and connections is hypothetical and may be exceeded.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
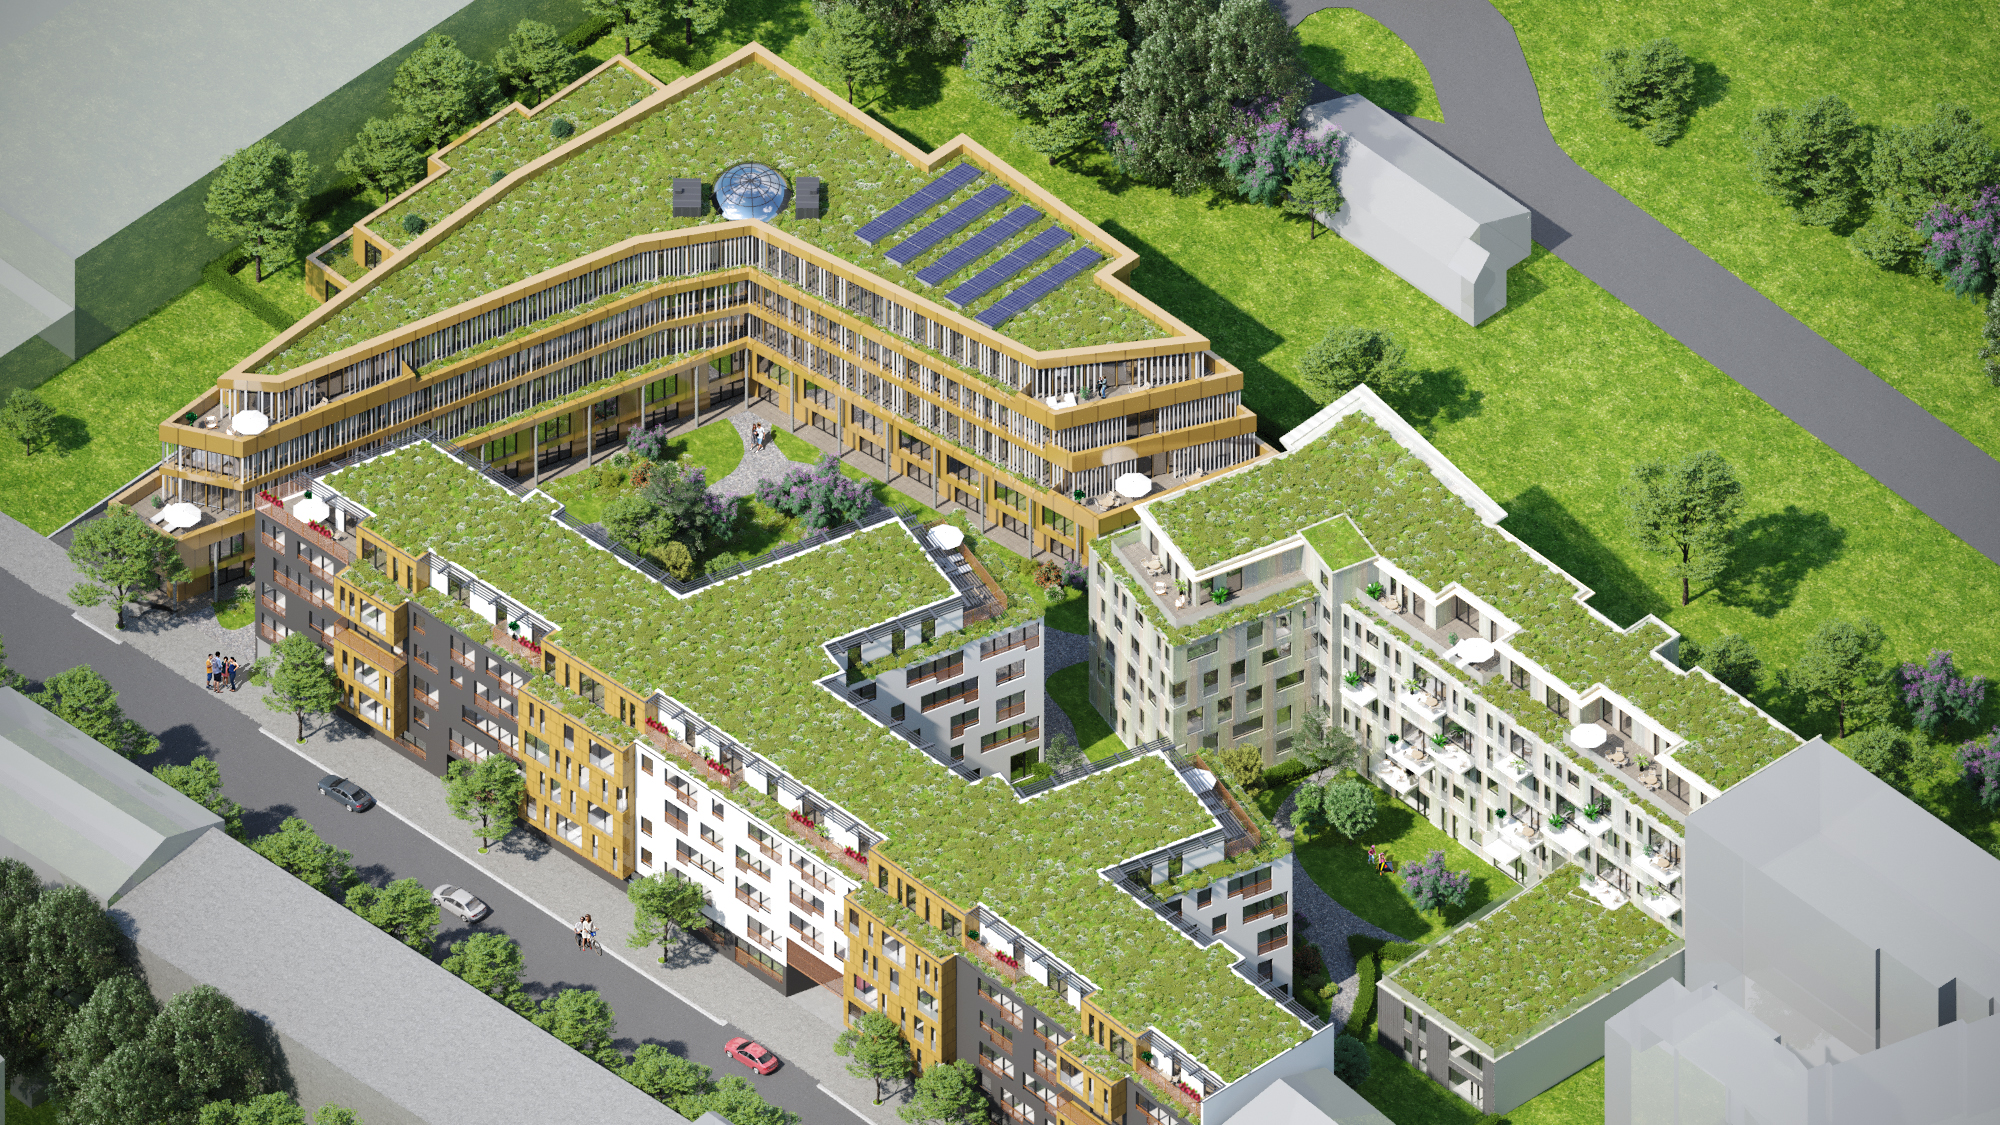
Asta-Nielsen-Straße 4

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Asta-Nielsen-Straße 4

Actual purchase price on request

Open presentation ↗

Project link ↗

Three planned residential buildings with 39 apartments in a June 2026 preliminary application, not an issued building permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-7.38 %-1,182,406 €
Base20.70 %2,993,995 €
Upside37.87 %5,275,795 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost14,466,005 €
Net exit proceeds17,460,000 €
Project profit / loss2,993,995 €
ROI over the whole project20.70 %
Illustrative annualized return6.47 %
Gross proceeds needed to break even14,913,407 €
Maximum purchase price at target ROI3,576,359 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: 2,989.54 m² BGF × €2,600/m². Assumed saleable residential area: 2,400 m² × €7,500/m², not verified Wohnfläche.
  • Netto 2,600.53 m², stated rentable area 2,914.24 m² and BGF are different measures. The 55.71/74.35 m² first-floor discrepancy and upper-floor classification remain unresolved.
  • Existing-building energy class G and 237.1 kWh/(m²a) do not apply to the new development. No parking sales or existing rental income are included.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
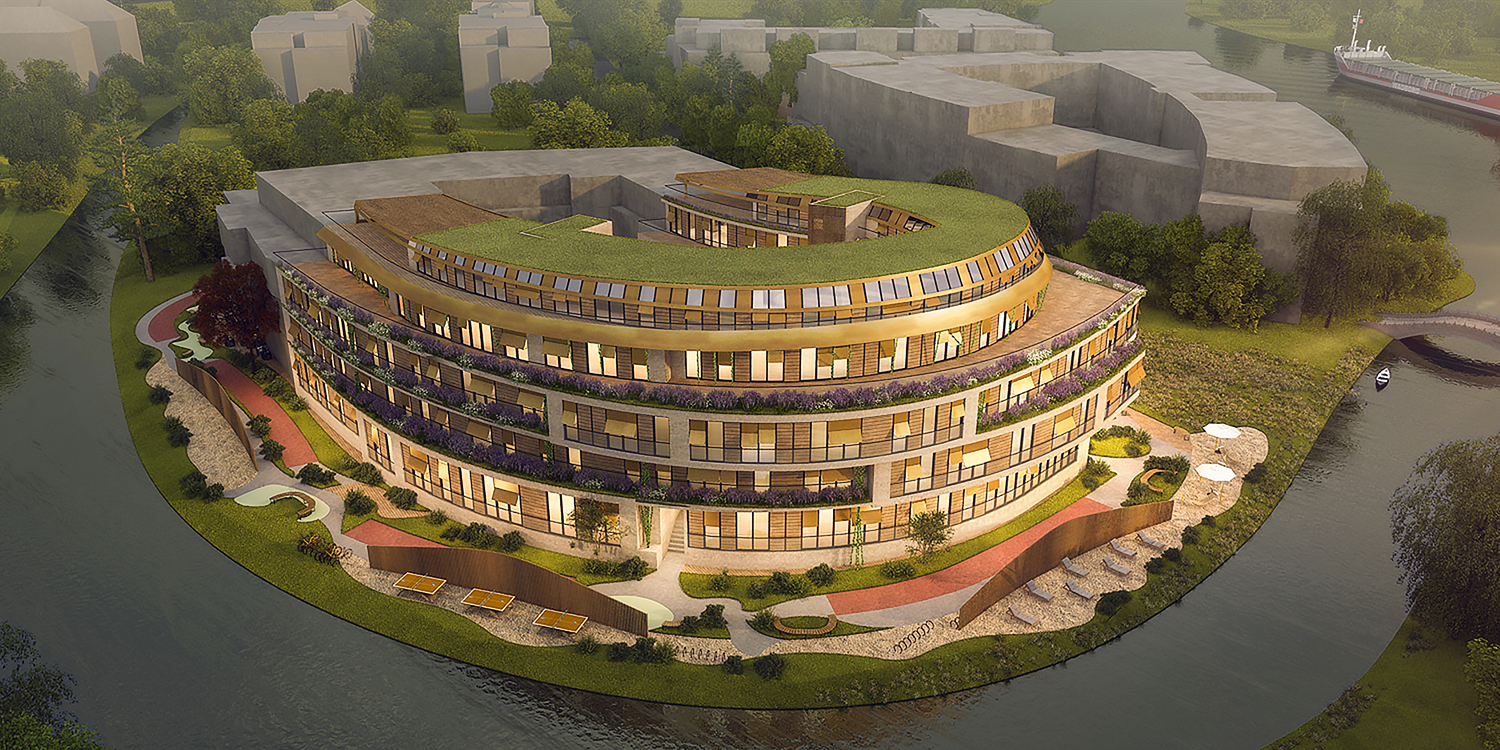
Liebermannstraße 27–37

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Liebermannstraße 27–37

Actual purchase price on request

Open presentation ↗

Project link ↗

Mixed-use development: 70 apartments, 39 new plus 2 existing commercial units and 95 underground parking spaces in the 2022 permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-25.27 %-28,182,807 €
Base-0.15 %-152,059 €
Upside15.10 %14,152,013 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost98,195,188 €
Net exit proceeds98,043,128 €
Project profit / loss-152,059 €
ROI over the whole project-0.15 %
Illustrative annualized return-0.04 %
Gross proceeds needed to break even101,232,152 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: total BGF 27,678.46 m² × €2,500/m²; an illustrative blended rate, not a DIN 276 estimate.
  • Exit: residential 8,019.24 m² × €8,000 + commercial 11,515.49 m² × €3,000 + 95 parking spaces × €25,000. Index I areas include credited balcony shares. All exit rates are assumed. Current permit validity and final saleable areas need confirmation.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
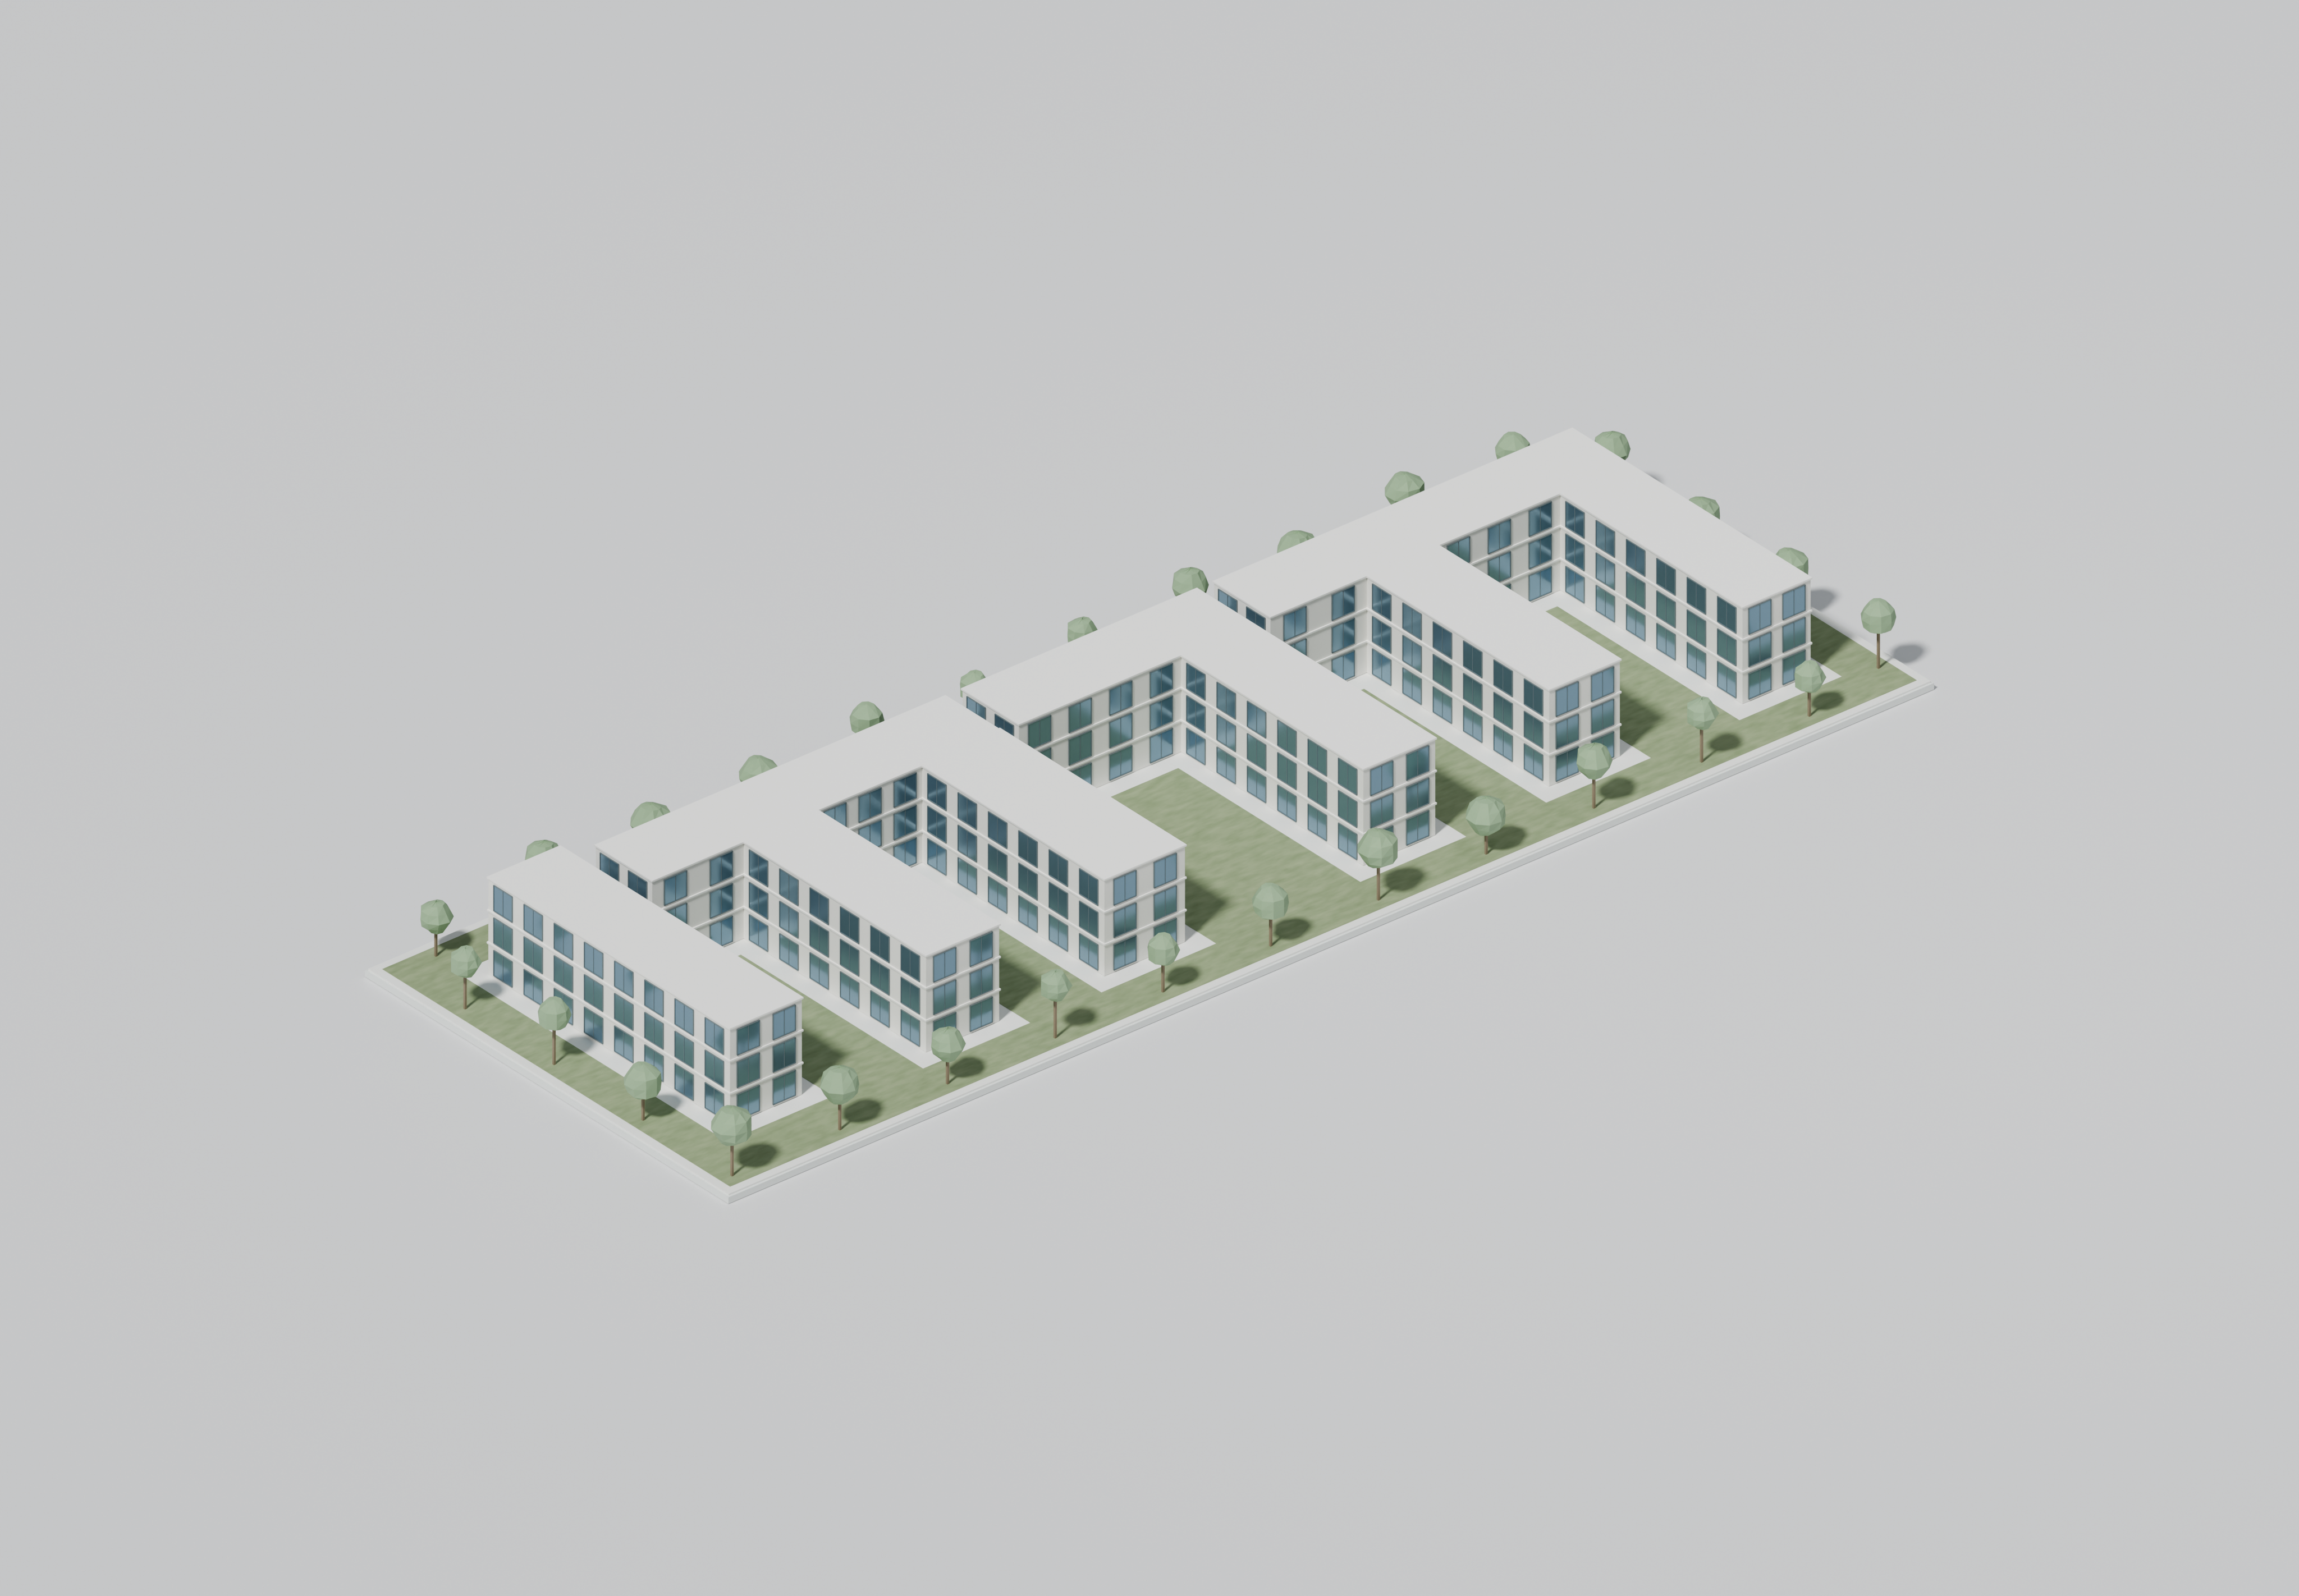
Spandauer Burgwall 46 / 48 / 50

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Spandauer Burgwall 46 / 48 / 50

Actual purchase price on request

Open presentation ↗

Project link ↗

A commercial temporary-accommodation concept with 123 units in two phases; these are not confirmed permanent residential apartments.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-28.37 %-12,049,302 €
Base-4.38 %-1,638,610 €
Upside10.22 %3,651,271 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost37,431,610 €
Net exit proceeds35,793,000 €
Project profit / loss-1,638,610 €
ROI over the whole project-4.38 %
Illustrative annualized return-1.11 %
Gross proceeds needed to break even38,589,289 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: enclosed BGF A 10,803.87 m² × €2,400/m². Hypothetical whole-project exit: 123 × €300,000 = €36.9m, not approved individual apartment sales.
  • No confirmed operator or purchaser, no capitalized invented rent. The €1m extra allowance is not a flood-protection, basement or fit-out estimate.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
Wilhelm-von-Siemens-Straße 32

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Wilhelm-von-Siemens-Straße 32

Actual purchase price on request

Open presentation ↗

Project link ↗

The February 2026 student-housing concept is separate from the older medical-use preliminary decision.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-14.08 %-4,232,174 €
Base13.82 %3,688,545 €
Upside30.83 %7,872,368 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost26,683,125 €
Net exit proceeds30,371,670 €
Project profit / loss3,688,545 €
ROI over the whole project13.82 %
Illustrative annualized return3.29 %
Gross proceeds needed to break even27,508,376 €
Maximum purchase price at target ROI2,251,455 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs use 7,455 m² of GFZ calculation area × €2,300/m² as a preliminary proxy, not confirmed BGF. Model exit: 70% of 7,455 m² × €6,000/m².
  • Area efficiency, prices, residential use and saleability are assumptions. No confirmed apartment count or transferred approval from the medical scheme.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR. Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

External context: IBB citywide new-build asking-price median, not a valuation of these projects; Berlin tax authority: 6% transfer tax. Other prices and budgets are independent illustrative assumptions. IBB 2025 · Berlin · Grunderwerbsteuer

عقارات استثمارية حالية

عقارات لاستثمارك

تظهر أولاً العقارات التي تتوفر لها بيانات إيجار. يُعرض مصدر البيانات في بطاقة كل عقار.

العائد الإيجاري الإجمالي = الإيجار الأساسي السنوي ÷ سعر الشراء. قبل تكاليف الشراء والتشغيل والتمويل والضرائب. ·

مباشرة إلى الحاسبة ↓

عقارك. حساباتك.

راجع تفاصيل العقار وعدّل سيناريو التمويل الخاص بك.

يورو · حساب شهري
بيانات العقار

شراء مبنى سكني وتجاري عالي الإنتاجية مكون من 12 غرفة في رينو

سعر الشراء—
المساحة السكنية—
حالة التأجير—
فئة كفاءة الطاقة—
الإيجار الأساسي / شهر—
إجمالي العائد الإيجاري—

ما ينبغي معرفته عن هذا العقار

نتيجتك الشهرية

كم يتبقى شهرياً؟

افتراضات حسابية قابلة للتعديل. ليست عرض تمويل.

ليست لديك أرقامك الخاصة بعد؟

عدّل القرض والافتراضات الأخرى +

تشمل الأموال الخاصة تكاليف الشراء. وتشمل تكاليف المالك النفقات التي لا تُحمّل للمستأجر ومخصص الاحتياطي المستمر. جميع النسب افتراضات قابلة للتعديل.

ما يتبقى لك شهرياً — قبل الضرائب—

الإيجار المستخدم في الحساب—
تكاليفك المستمرة—
دفعة قرضك—
عرض العوائد كنسبة مئوية +

يقارن العائد الإيجار السنوي بسعر الشراء. وهو ليس المبلغ المتبقي بعد دفع القرض.

إجمالي العائد الإيجاري—
صافي العائد قبل التمويل¹—
ماذا لو انخفض الإيجار أو ارتفعت الفائدة؟ +

¹ الإيجار السنوي بعد الخسارة المفترضة ناقص تكاليف المالك، مقسوماً على سعر العقار مع تكاليف الشراء. دون الضرائب أو ارتفاع القيمة أو التجديد لمرة واحدة أو تكاليف البيع. دفعة القرض محسوبة على أساس الدفعة السنوية الأولية، وليست جدول سداد كاملاً.

ناقش نتيجتي ↗

افهم الفكرة في 30 ثانية

كيف يعمل العقار المؤجّر؟

تشتري عقاراً كاملاً لتأجيره. لا تستثمر أموالاً عبر هذا الموقع.

1

تشتري عقاراً.

تدفع من أموالك الخاصة، وبقرض عند الحاجة. تُضاف تكاليف الشراء إلى سعر العقار.

2

تحصل على الإيجار.

استخدم الإيجار دون التدفئة ورسوم التشغيل. الأموال المخصصة لهذه الفواتير ليست دخلاً متاحاً للإنفاق بحرية.

3

تدفع النفقات.

تُخصم دفعة القرض وتكاليفك المستمرة. وتعرض الحاسبة ما يتبقى.

الإيجار بعد الخسارة المفترضة−تكاليفك المستمرة−دفعة القرض=ما يتبقى شهرياً
خطوات مدروسة دون اختصار.

من المستندات إلى قرار واضح.

01

شاهد الصورة الكاملة.

تكوّن نشرة العقار وعقد الإيجار والميزانية وحالة العقار صورة متكاملة.

02

احسب بالتفصيل.

الإيجار والتمويل والتكاليف المستمرة، وفق افتراضاتك ومع مراعاة المخاطر.

03

ناقش الأمر شخصياً.

ناقش الأسئلة والشروط المفتوحة قبل اتخاذ الخطوة التالية.

أسئلة مهمة، إجابات واضحة

ما ينبغي فهمه قبل الشراء.

هل يعني الإيجار ربحاً تلقائياً؟

لا. تُخصم التكاليف المستمرة ودفعات القرض إن وجدت من الإيجار. تعرض الحاسبة ما يتبقى قبل الضرائب.

ماذا تعني النتيجة السالبة؟

في هذا الحساب، لا يغطي الإيجار المدخل جميع النفقات. ستحتاج إلى دفع المبلغ المعروض شهرياً من أموال أخرى.

لماذا بعض الحقول فارغة؟

لا تتوفر بعد بيانات متحقق منها لهذا العقار. لا نختلق قيمة الإيجار. أدخل القيم المعروفة أو اطلب منا توضيح المستندات.

هل يمكن الاعتماد على النتيجة؟

هذا نموذج يعتمد على مدخلاتك، وليس ضماناً. انخفاض الإيجار أو الإصلاحات أو تغير شروط القرض يغيّر النتيجة. الضرائب والتجديدات لمرة واحدة وتكاليف البيع غير مشمولة.

ماذا يحدث عند إرسال استفسار؟

تتلقى Everpeak بيانات اتصالك والعقار المختار وحسابك. ثم يمكننا مناقشة النقاط المفتوحة. لا يُلزمك الاستفسار بشراء عقار.

EVERPEAK PRIVATE

من مليون يورو. رأس مالك. رؤيتك.

ناقش استثماراً خاصاً ↗
5,0 ★★★★★ 33 تقييماً على Google

«تواصل وخدمة ممتازان. بافل متجاوب وودود ومحترف بحق.» — Angela

«يقف إلى جانب العميل ويدافع عن مصالحه، وهذا نادر في برلين! أوصي به بشدة.» — Artem S.

«في كل مرة كانت النتيجة أفضل مما خططنا له.» — Natalia H.

ترجمة من الروسية

قراءة جميع التقييمات على Google ←

الخطوة التالية

أسئلتك. ننظر فيها معاً.

نناقش العقار وسيناريو حسابك.
بشكل شخصي وواضح ودون التزام.

بإرسال الاستفسار، ترسل بيانات اتصالك والحساب الحالي إلى Everpeak. إشعار الخصوصية