Everpeak Properties
GayrimenkullerYatırım hesaplayıcısıÖzel danışmanlık · 1 milyon € ve üzeri
EVERPEAK INVESTMENT

Yatırım için gayrimenkuller.

Satın alma fiyatlarını, mevcut kira bilgilerini ve brüt getirileri karşılaştırın. Bir gayrimenkulü inceleyin ve aylık sonucunuzu hesaplayın.

EVERPEAK · DEVELOPMENT

Development projects

Five projects with reviewed source documents and separate scenario economics. Actual purchase prices are on request. All purchase prices, budgets and exit values below are illustrative assumptions.

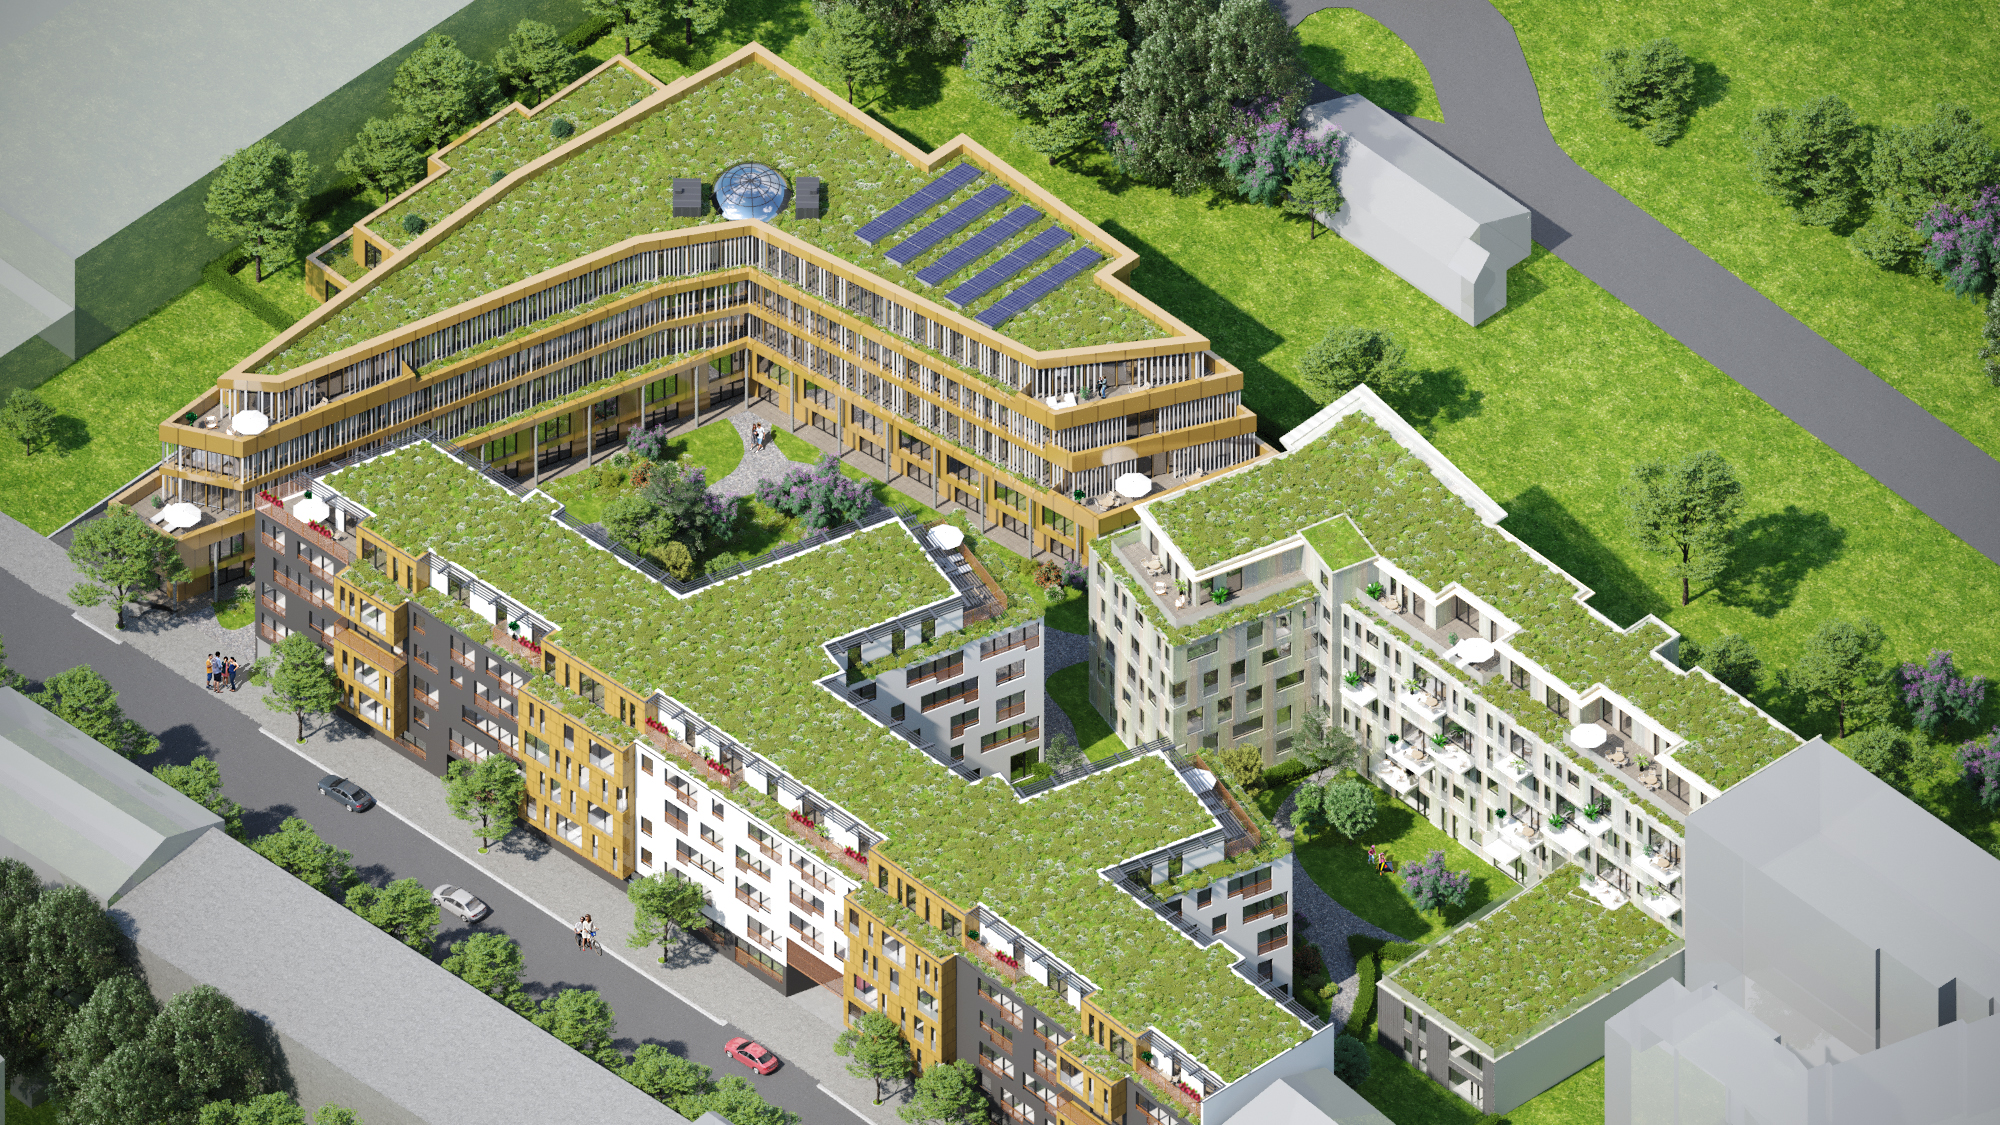
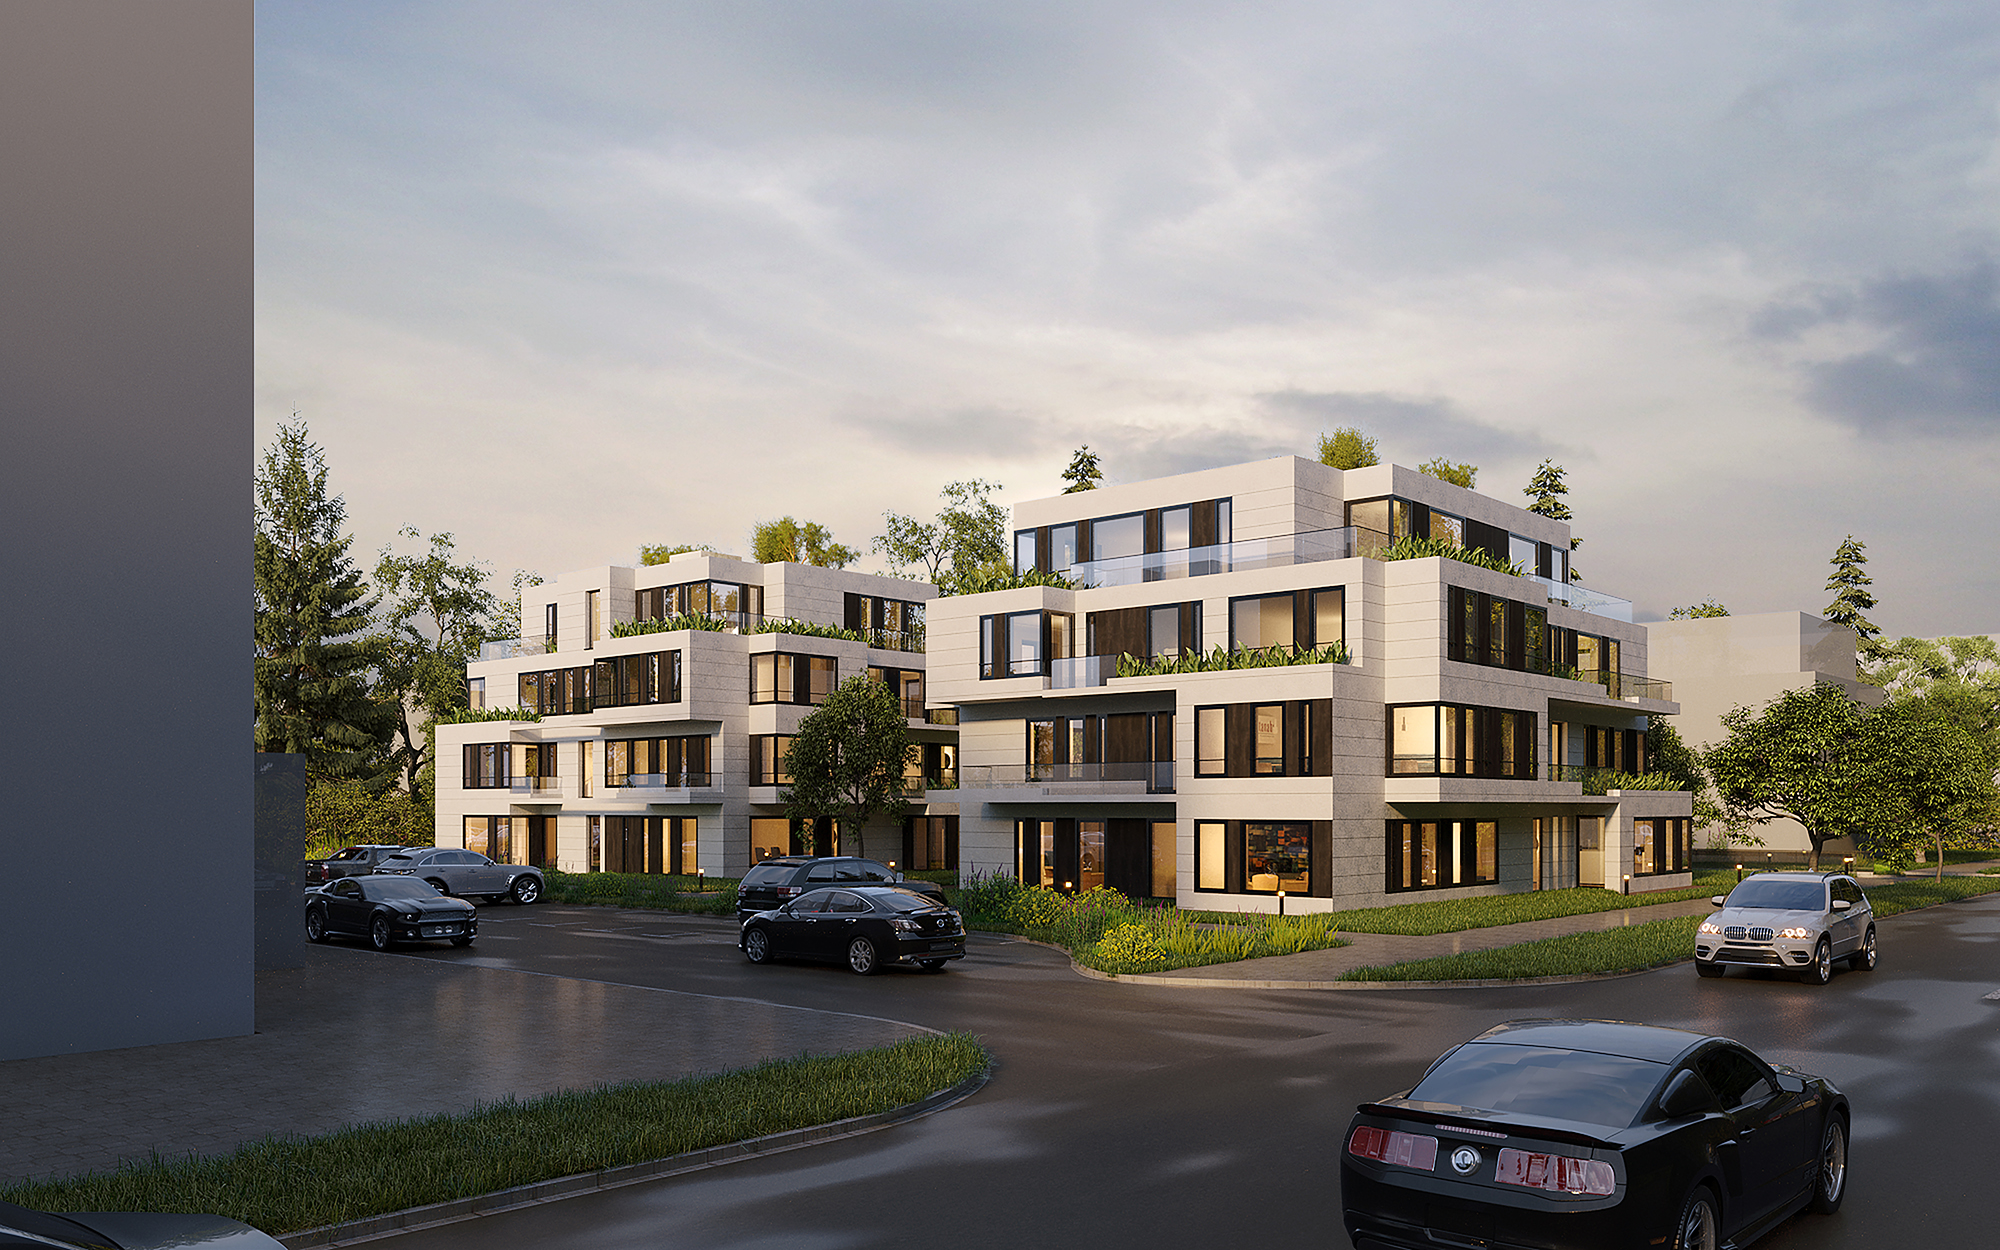
Liebermannstraße 27–37

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Liebermannstraße 27–37

Actual purchase price on request

Open presentation ↗

Project link ↗

Mixed-use development: 70 apartments, 39 new plus 2 existing commercial units and 95 underground parking spaces in the 2022 permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-25.27 %-28,182,807 €
Base-0.15 %-152,059 €
Upside15.10 %14,152,013 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost98,195,188 €
Net exit proceeds98,043,128 €
Project profit / loss-152,059 €
ROI over the whole project-0.15 %
Illustrative annualized return-0.04 %
Gross proceeds needed to break even101,232,152 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: total BGF 27,678.46 m² × €2,500/m²; an illustrative blended rate, not a DIN 276 estimate.
  • Exit: residential 8,019.24 m² × €8,000 + commercial 11,515.49 m² × €3,000 + 95 parking spaces × €25,000. Index I areas include credited balcony shares. All exit rates are assumed. Current permit validity and final saleable areas need confirmation.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
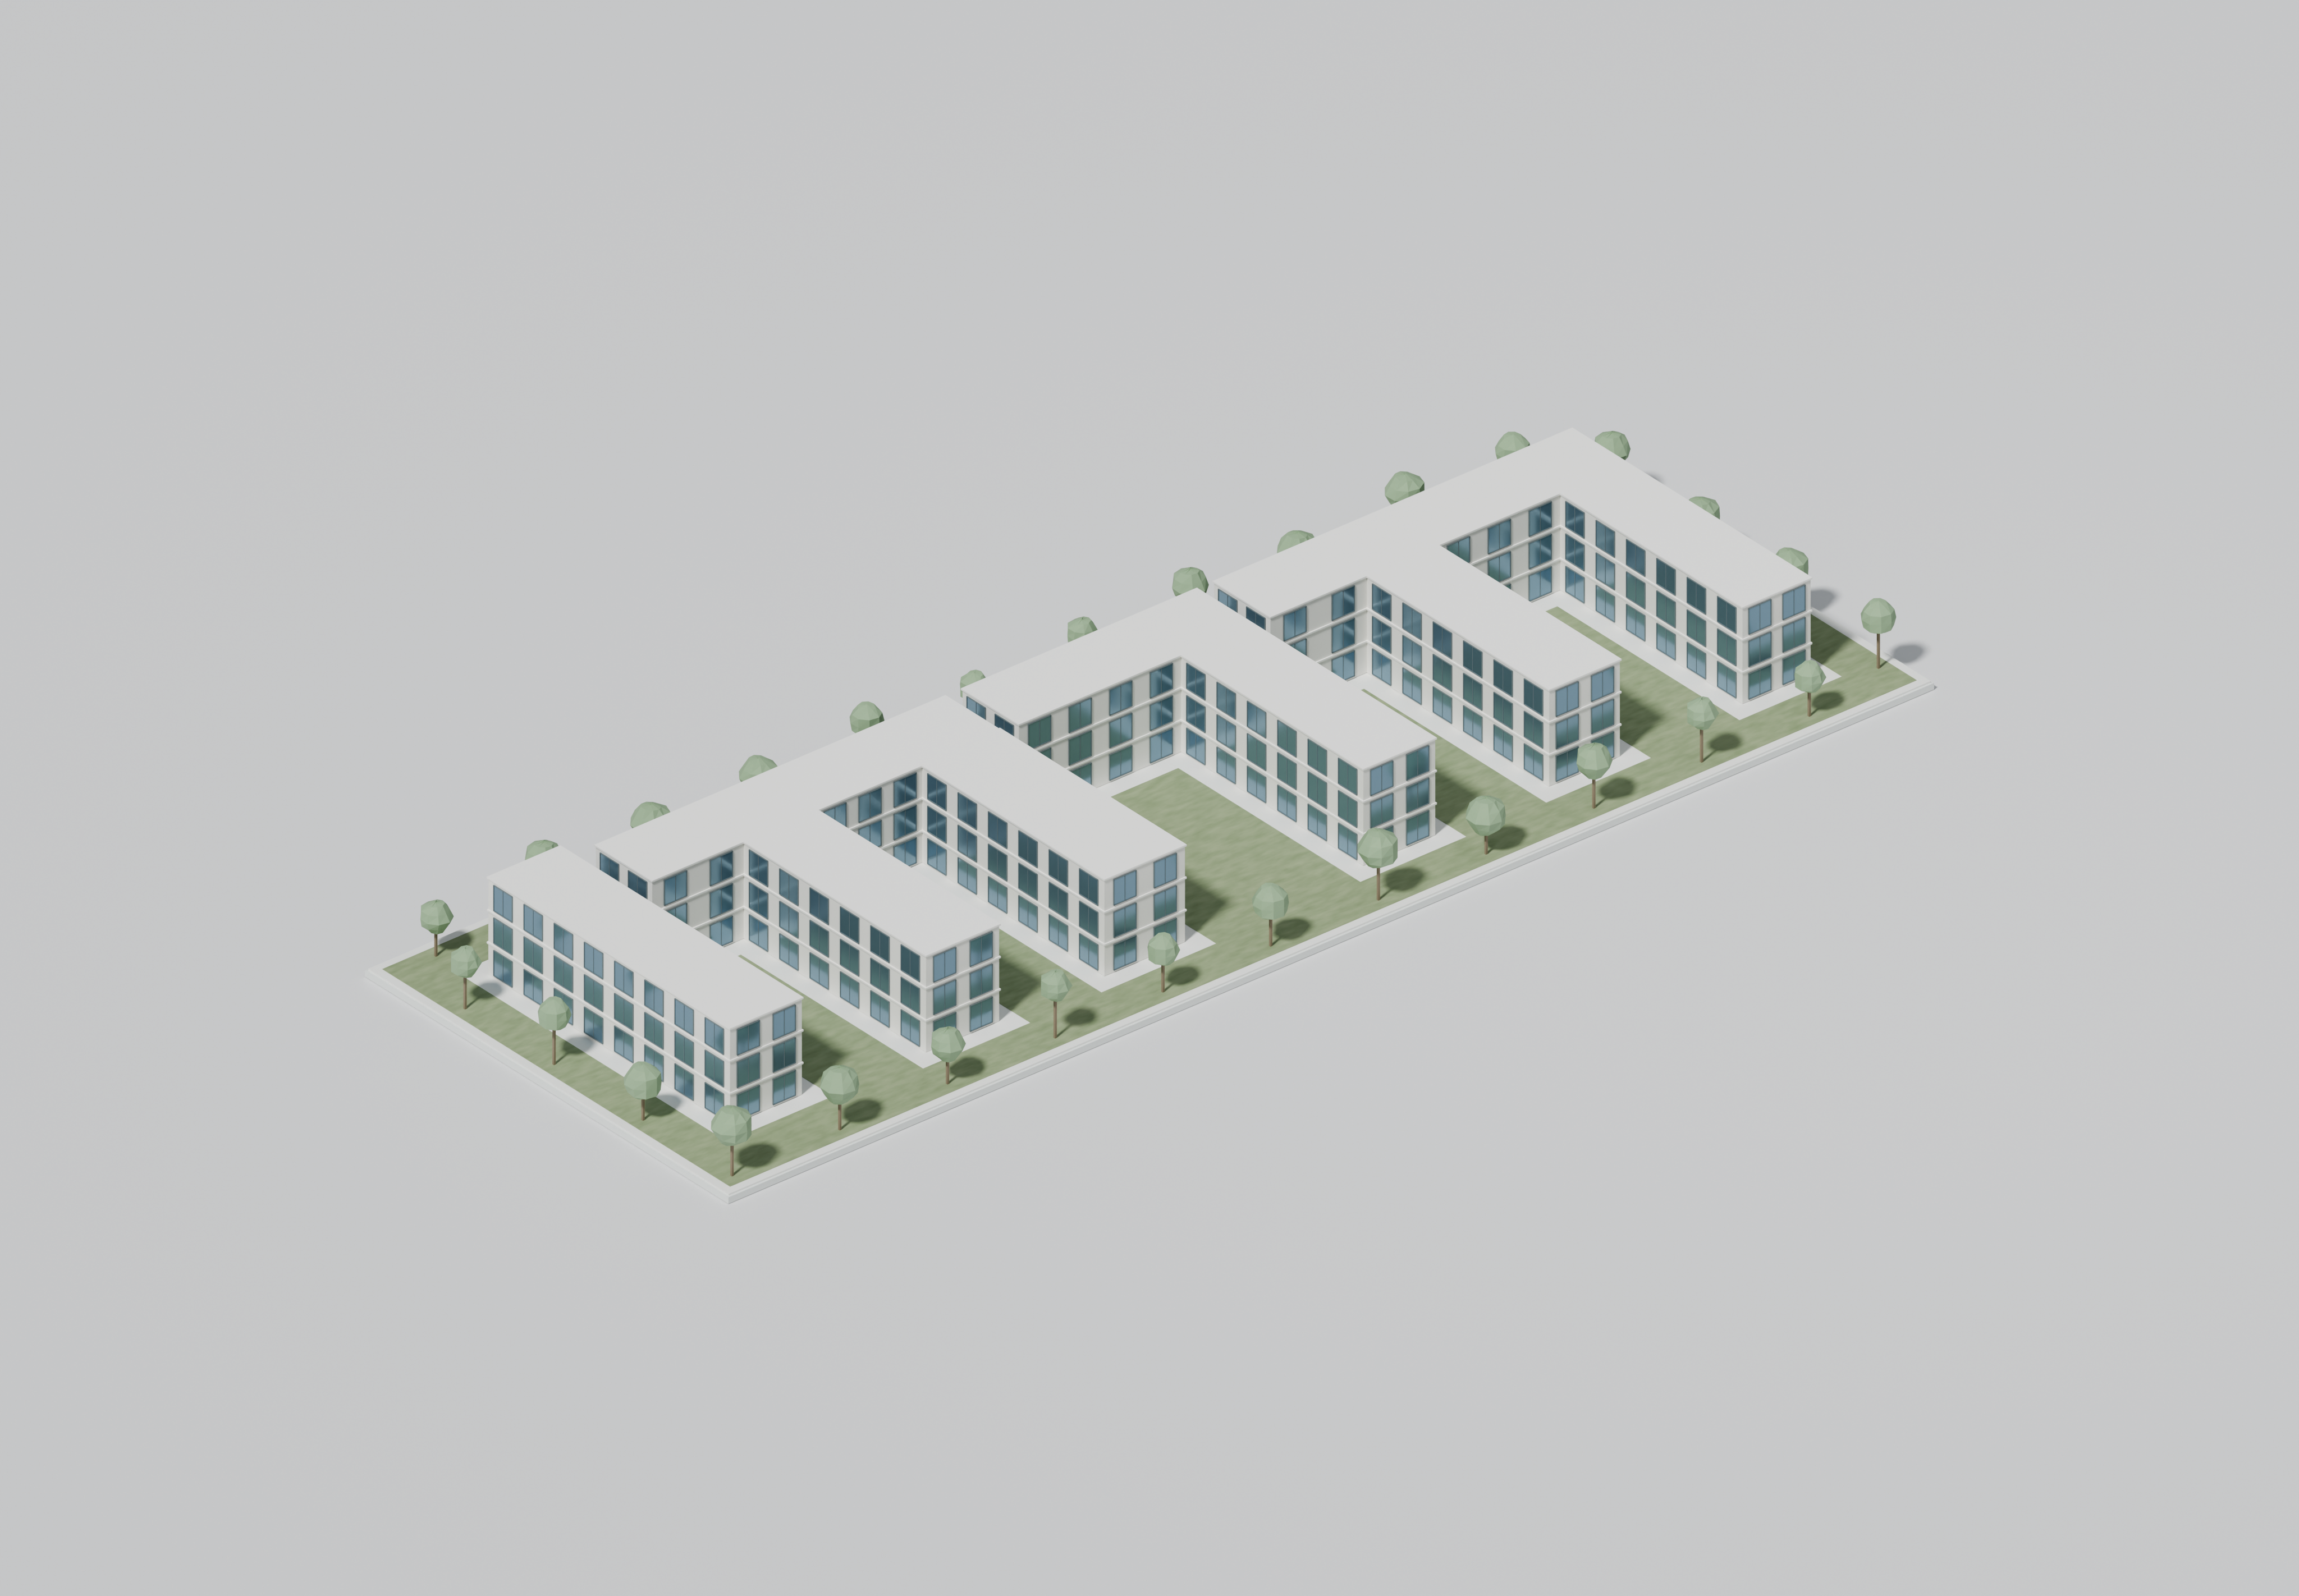
Asta-Nielsen-Straße 4

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Asta-Nielsen-Straße 4

Actual purchase price on request

Open presentation ↗

Project link ↗

Three planned residential buildings with 39 apartments in a June 2026 preliminary application, not an issued building permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-7.38 %-1,182,406 €
Base20.70 %2,993,995 €
Upside37.87 %5,275,795 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost14,466,005 €
Net exit proceeds17,460,000 €
Project profit / loss2,993,995 €
ROI over the whole project20.70 %
Illustrative annualized return6.47 %
Gross proceeds needed to break even14,913,407 €
Maximum purchase price at target ROI3,576,359 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: 2,989.54 m² BGF × €2,600/m². Assumed saleable residential area: 2,400 m² × €7,500/m², not verified Wohnfläche.
  • Netto 2,600.53 m², stated rentable area 2,914.24 m² and BGF are different measures. The 55.71/74.35 m² first-floor discrepancy and upper-floor classification remain unresolved.
  • Existing-building energy class G and 237.1 kWh/(m²a) do not apply to the new development. No parking sales or existing rental income are included.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
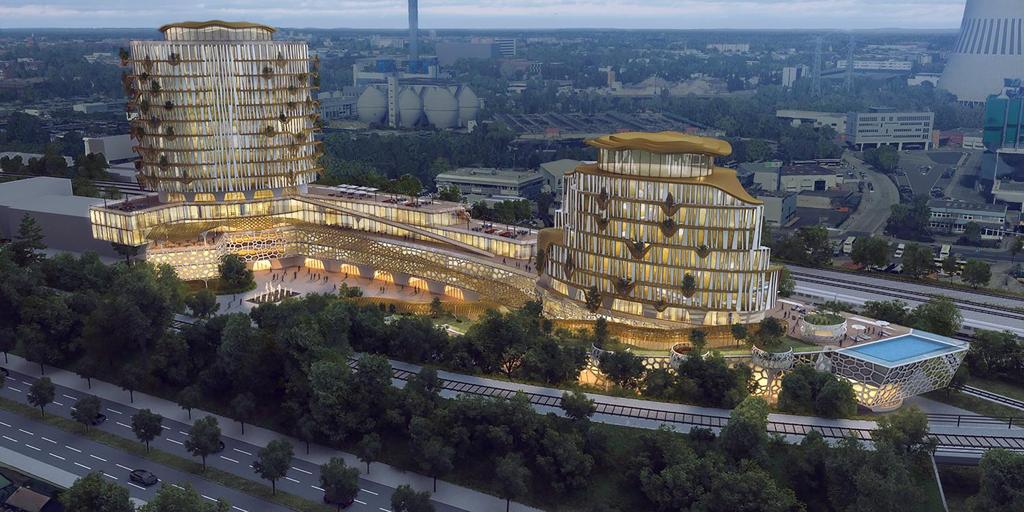
Klärwerkstraße 1 / 1A

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Klärwerkstraße 1 / 1A

Actual purchase price on request

Open presentation ↗

Project link ↗

Commercial development potential based on a 2020 study; railway-purpose release and contaminated-land investigations remain unresolved.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-27.41 %-27,762,387 €
Base-3.55 %-3,188,355 €
Upside10.92 %9,370,202 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost89,699,284 €
Net exit proceeds86,510,928 €
Project profit / loss-3,188,355 €
ROI over the whole project-3.55 %
Illustrative annualized return-0.72 %
Gross proceeds needed to break even92,473,488 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Uses only Real Case 31,852.33 m² BGF, not the larger theoretical concepts. Hard costs: BGF × €1,900/m². Assumed saleable floor area: 80% of BGF × €3,500/m². Neither the efficiency ratio nor exit price is verified.
  • €4m extra-works allowance for investigations, remediation/site preparation and connections is hypothetical and may be exceeded.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
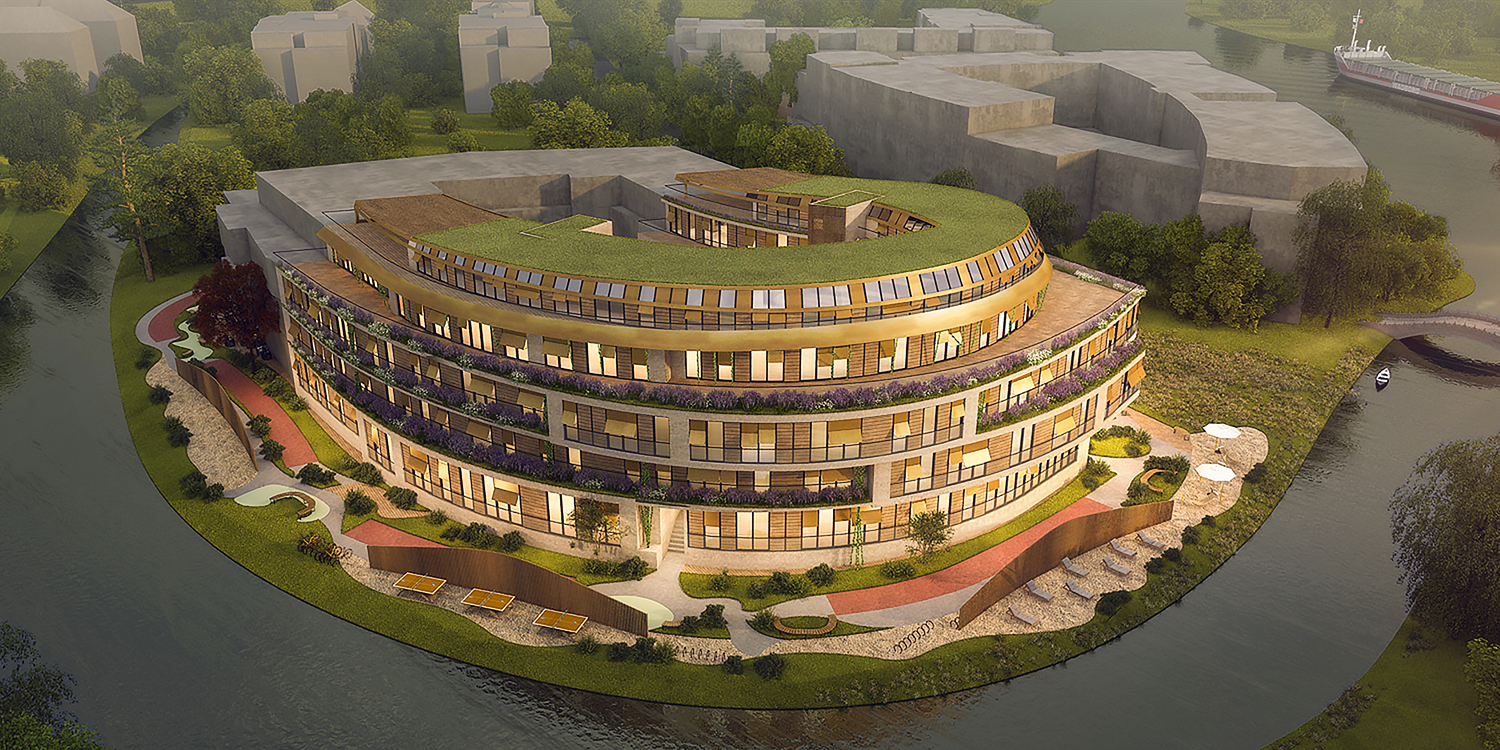
Spandauer Burgwall 46 / 48 / 50

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Spandauer Burgwall 46 / 48 / 50

Actual purchase price on request

Open presentation ↗

Project link ↗

A commercial temporary-accommodation concept with 123 units in two phases; these are not confirmed permanent residential apartments.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-28.37 %-12,049,302 €
Base-4.38 %-1,638,610 €
Upside10.22 %3,651,271 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost37,431,610 €
Net exit proceeds35,793,000 €
Project profit / loss-1,638,610 €
ROI over the whole project-4.38 %
Illustrative annualized return-1.11 %
Gross proceeds needed to break even38,589,289 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: enclosed BGF A 10,803.87 m² × €2,400/m². Hypothetical whole-project exit: 123 × €300,000 = €36.9m, not approved individual apartment sales.
  • No confirmed operator or purchaser, no capitalized invented rent. The €1m extra allowance is not a flood-protection, basement or fit-out estimate.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
Wilhelm-von-Siemens-Straße 32

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Wilhelm-von-Siemens-Straße 32

Actual purchase price on request

Open presentation ↗

Project link ↗

The February 2026 student-housing concept is separate from the older medical-use preliminary decision.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-14.08 %-4,232,174 €
Base13.82 %3,688,545 €
Upside30.83 %7,872,368 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost26,683,125 €
Net exit proceeds30,371,670 €
Project profit / loss3,688,545 €
ROI over the whole project13.82 %
Illustrative annualized return3.29 %
Gross proceeds needed to break even27,508,376 €
Maximum purchase price at target ROI2,251,455 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs use 7,455 m² of GFZ calculation area × €2,300/m² as a preliminary proxy, not confirmed BGF. Model exit: 70% of 7,455 m² × €6,000/m².
  • Area efficiency, prices, residential use and saleability are assumptions. No confirmed apartment count or transferred approval from the medical scheme.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR. Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

External context: IBB citywide new-build asking-price median, not a valuation of these projects; Berlin tax authority: 6% transfer tax. Other prices and budgets are independent illustrative assumptions. IBB 2025 · Berlin · Grunderwerbsteuer

GÜNCEL YATIRIM GAYRİMENKULLERİ

Yatırımınız için gayrimenkuller

Kira bilgisi olan gayrimenkuller önce gösterilir. Her kartta bu bilgilerin kaynağı belirtilir.

Brüt kira getirisi = yıllık giderler hariç kira ÷ satın alma fiyatı. Satın alma ve işletme giderleri, finansman ve vergiler öncesi. ·

Doğrudan hesaplayıcıya git ↓

Gayrimenkulünüz. Hesabınız.

Gayrimenkul ayrıntılarını inceleyin ve kendi finansman senaryonuzu düzenleyin.

EUR · aylık hesaplama
Gayrimenkul bilgileri

Rhinow'da yüksek verimli 12 odalı bir konut ve ticari bina satın alın

Satın alma fiyatı—
Yaşam alanı—
Kiralama durumu—
Enerji sınıfı—
Giderler hariç kira / ay—
Brüt kira getirisi—

Bu gayrimenkul hakkında bilmeniz gerekenler

AYLIK SONUCUNUZ

Ay sonunda ne kalır?

Değiştirilebilir model varsayımlarıdır. Finansman teklifi değildir.

Kendi rakamlarınız henüz yok mu?

Kredi ve diğer varsayımları düzenleyin +

Özkaynak, ek satın alma giderlerini kapsar. Malik giderleri, kiracıya yansıtılamayan giderleri ve düzenli yedek fon katkınızı içerir. Tüm yüzdeler serbestçe seçilen varsayımlardır.

Vergi öncesi aylık kalan tutar—

Hesaplamada esas alınan kira—
Düzenli giderleriniz—
Kredi taksitiniz—
Yüzde olarak getiriyi göster +

Getiri, yıllık kirayı satın alma fiyatıyla karşılaştırır. Kredi taksiti ödendikten sonra elinizde kalan para değildir.

Brüt kira getirisi—
Finansman öncesi net getiri¹—
Kira düşerse veya faiz yükselirse ne olur? +

¹ Kira kaybı varsayımı sonrası yıllık kiradan malik giderleri çıkarılır ve ek satın alma giderleri dahil satın alma fiyatına bölünür. Vergiler, değer artışı, tek seferlik yenileme ve satış giderleri hariçtir. Kredi taksiti başlangıçtaki yıllık toplam ödeme üzerinden hesaplanır; bir ödeme planı değildir.

30 SANİYEDE ANLAYIN

Kiraya verilen bir gayrimenkul nasıl işler?

Burada kiraya vermek üzere bir gayrimenkulün tamamını satın alırsınız. Bu web sitesi üzerinden para yatırmazsınız.

1

Bir gayrimenkul satın alırsınız.

Kendi paranızla ve gerekirse krediyle ödeme yaparsınız. Satın alma fiyatına ek satın alma giderleri de eklenir.

2

Kira geliri elde edersiniz.

Isıtma ve işletme giderleri hariç net kirayı esas alın. Isıtma ve işletme giderleri için alınan para, serbestçe kullanabileceğiniz gelir değildir.

3

Giderleri ödersiniz.

Kredi taksiti ve size ait düzenli giderler düşülür. Geriye ne kaldığını hesaplayıcıda görebilirsiniz.

Kira kaybı varsayımı sonrası kira−Düzenli giderleriniz−Kredi taksiti=Aylık kalan tutar
SAĞLAM BİR SÜREÇ. KESTİRME YOL YOK.

Belgelerden net bir karara.

01

Bütün resmi görün.

Tanıtım dosyası, kira sözleşmesi, yıllık bina bütçesi ve gayrimenkulün durumu birlikte değerlendirilir.

02

Ayrıntılı hesaplayın.

Kira, finansman ve düzenli giderler. Sizin varsayımlarınızla ve riskler göz önünde bulundurularak.

03

Yüz yüze netleştirin.

Bir sonraki adımı atmadan önce açık soruları ve koşulları görüşün.

İYİ SORULAR, AÇIK CEVAPLAR

Satın almadan önce bilmeniz gerekenler.

“Kira” otomatik olarak “kâr” anlamına mı gelir?

Hayır. Kiradan düzenli giderler ve varsa kredi taksiti düşülür. Hesaplayıcı, sonrasında vergi öncesi kalan tutarı gösterir.

Sonucun eksi çıkması ne anlama gelir?

Bu hesaplamada girilen kira, tüm giderleri karşılamaya yetmiyor. Gösterilen tutarı her ay diğer kaynaklarınızdan tamamlamanız gerekir.

Bazı alanlar neden boş?

Bu gayrimenkul için henüz doğrulanmış bilgiler mevcut değil. Kira tutarı uydurmuyoruz. Bildiğiniz değerleri girin veya belgeleri bizimle netleştirin.

Sonuca güvenebilir miyim?

Bu, girdilerinize dayalı bir model hesaplamadır; taahhüt değildir. Daha düşük kira, onarımlar veya farklı kredi koşulları sonucu değiştirir. Vergiler, tek seferlik yenilemeler ve satış giderleri hesaba katılmaz.

Bir talep gönderdiğimde ne olur?

Everpeak iletişim bilgilerinizi, seçtiğiniz gayrimenkulü ve hesaplamanızı alır. Böylece açık konuları sizinle görüşebiliriz. Talep göndermek, gayrimenkul satın alma işlemi oluşturmaz.

EVERPEAK PRIVATE

1 milyon avrodan itibaren. Sermayeniz. Bakış açınız.

Özel yatırımı görüşelim ↗
5,0 ★★★★★

33 Google'daki yorumlar

«Mükemmel iletişim ve servis. Pavel duyarlı, cana yakın ve gerçek bir profesyonel.» — Angela

«Müşterinin yanında yer alıyor ve onların çıkarlarını savunuyor; Berlin'de nadir görülen bir durum bu! Şiddetle tavsiye edilir.» — Artem S.

«Her seferinde sonuç planladığımızdan daha iyiydi.» — Natalia H.

Rusça'dan çevrildi

Google'daki tüm yorumları okuyun

SONRAKİ ADIM

Sorularınız. Birlikte değerlendirelim.

Gayrimenkulü ve hesaplama senaryonuzu görüşürüz.
Kişisel, somut ve bağlayıcı olmayan bir görüşme.

Talebinizle birlikte iletişim bilgilerinizi ve mevcut hesaplama senaryonuzu Everpeak’e gönderirsiniz. Gizlilik bilgileri