Everpeak Properties
املاکمحاسبه‌گر سرمایه‌گذاریمشاوره اختصاصی · از ۱ میلیون یورو
EVERPEAK INVESTMENT

املاک برای سرمایه‌گذاری.

قیمت خرید، اطلاعات موجود اجاره و بازده ناخالص را مقایسه کنید. ملک را بررسی کنید و نتیجه ماهانه خود را محاسبه کنید.

EVERPEAK · DEVELOPMENT

Development projects

Five projects with reviewed source documents and separate scenario economics. Actual purchase prices are on request. All purchase prices, budgets and exit values below are illustrative assumptions.

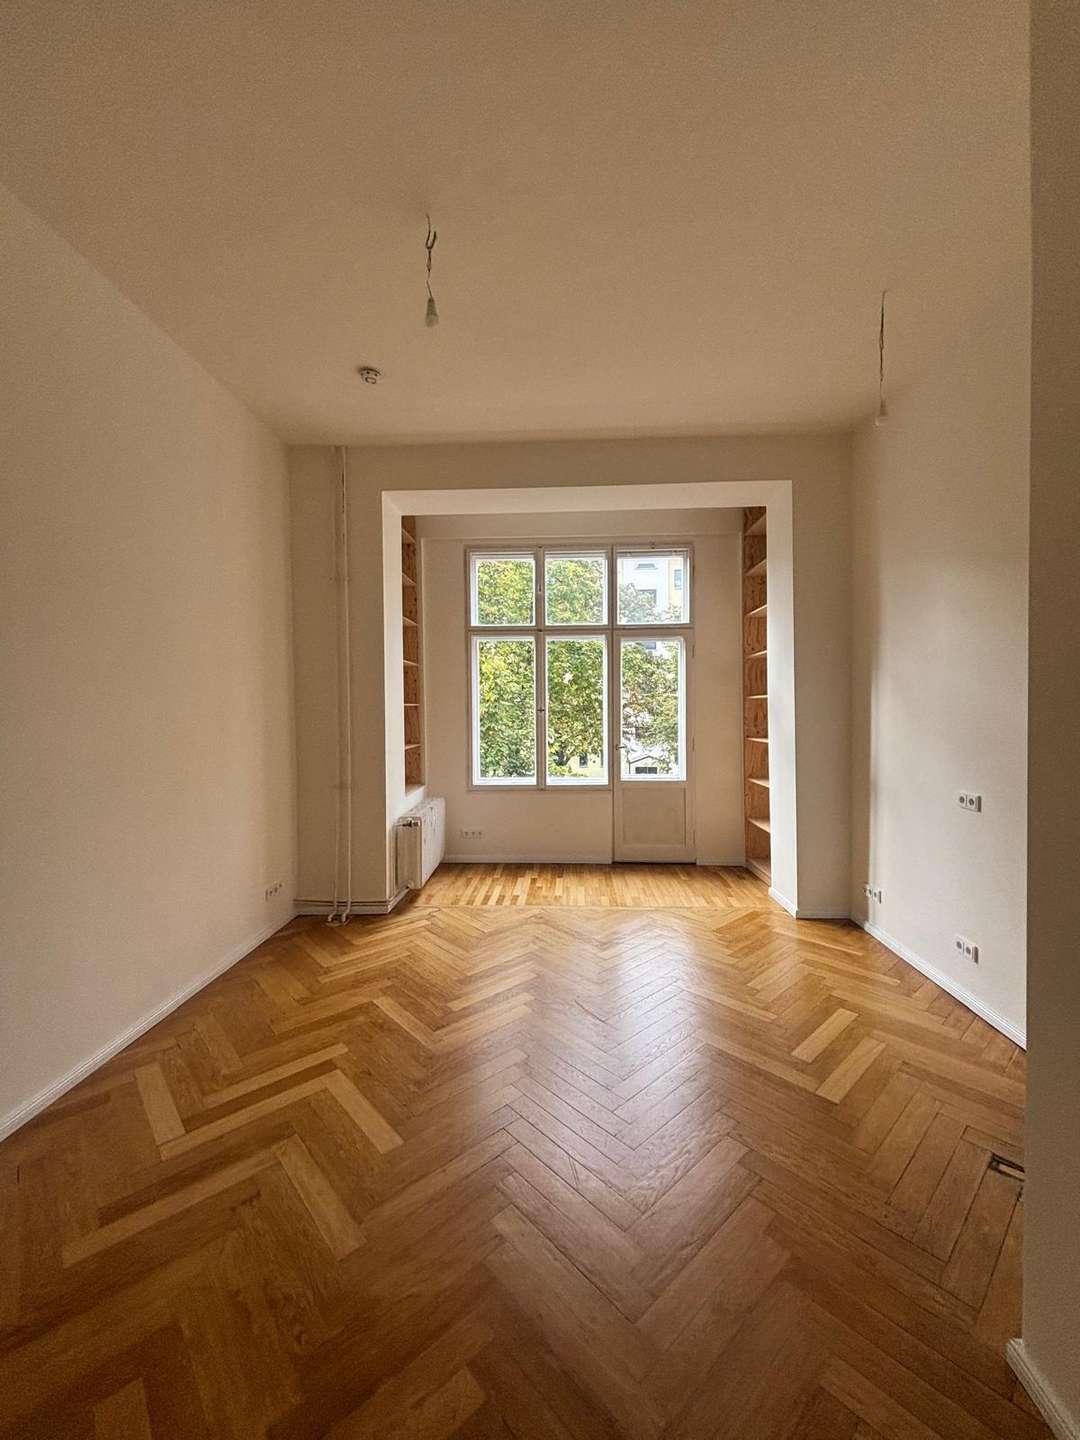
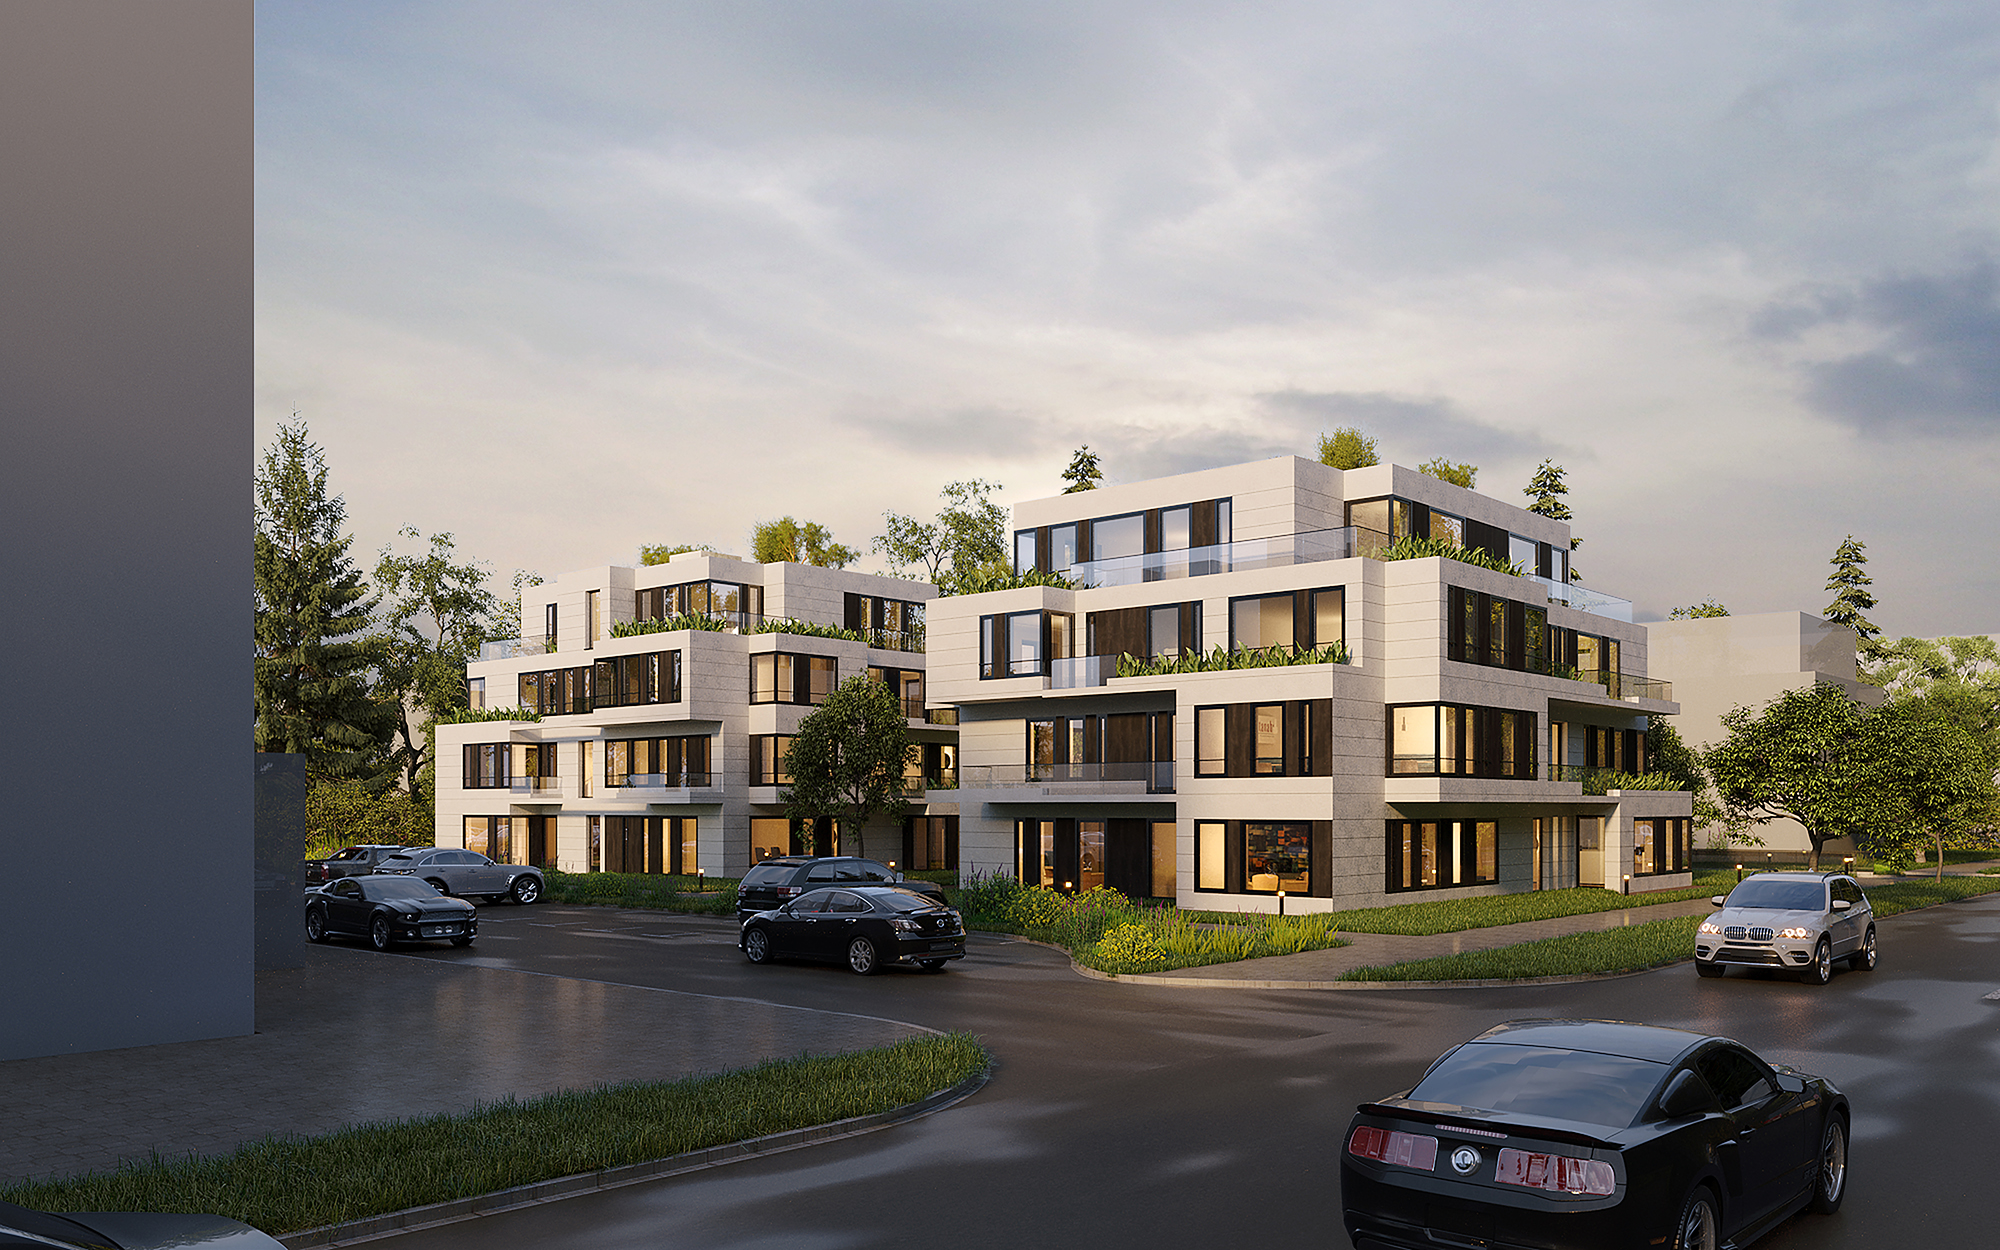
Wilhelm-von-Siemens-Straße 32

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Wilhelm-von-Siemens-Straße 32

Actual purchase price on request

Open presentation ↗

Project link ↗

The February 2026 student-housing concept is separate from the older medical-use preliminary decision.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-14.08 %-4,232,174 €
Base13.82 %3,688,545 €
Upside30.83 %7,872,368 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost26,683,125 €
Net exit proceeds30,371,670 €
Project profit / loss3,688,545 €
ROI over the whole project13.82 %
Illustrative annualized return3.29 %
Gross proceeds needed to break even27,508,376 €
Maximum purchase price at target ROI2,251,455 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs use 7,455 m² of GFZ calculation area × €2,300/m² as a preliminary proxy, not confirmed BGF. Model exit: 70% of 7,455 m² × €6,000/m².
  • Area efficiency, prices, residential use and saleability are assumptions. No confirmed apartment count or transferred approval from the medical scheme.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
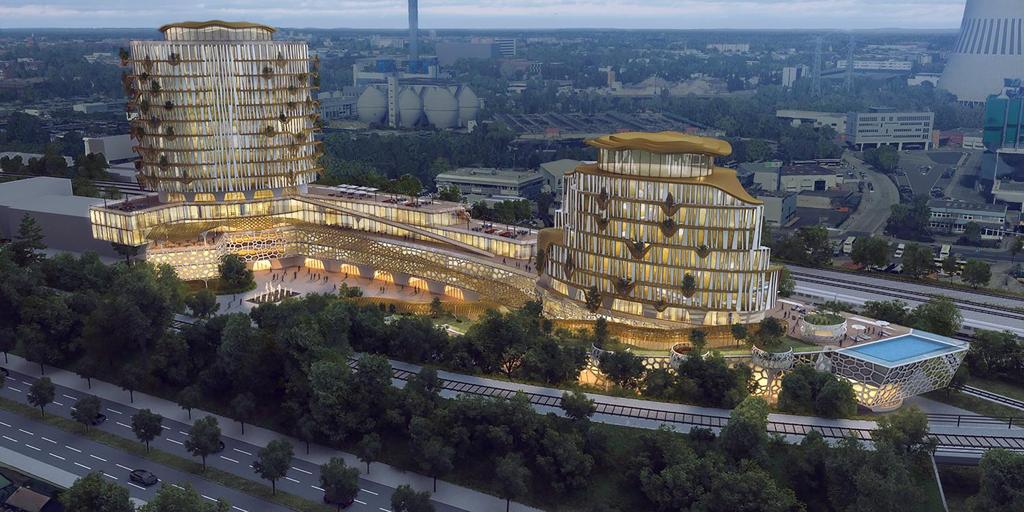
Asta-Nielsen-Straße 4

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Asta-Nielsen-Straße 4

Actual purchase price on request

Open presentation ↗

Project link ↗

Three planned residential buildings with 39 apartments in a June 2026 preliminary application, not an issued building permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-7.38 %-1,182,406 €
Base20.70 %2,993,995 €
Upside37.87 %5,275,795 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost14,466,005 €
Net exit proceeds17,460,000 €
Project profit / loss2,993,995 €
ROI over the whole project20.70 %
Illustrative annualized return6.47 %
Gross proceeds needed to break even14,913,407 €
Maximum purchase price at target ROI3,576,359 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: 2,989.54 m² BGF × €2,600/m². Assumed saleable residential area: 2,400 m² × €7,500/m², not verified Wohnfläche.
  • Netto 2,600.53 m², stated rentable area 2,914.24 m² and BGF are different measures. The 55.71/74.35 m² first-floor discrepancy and upper-floor classification remain unresolved.
  • Existing-building energy class G and 237.1 kWh/(m²a) do not apply to the new development. No parking sales or existing rental income are included.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
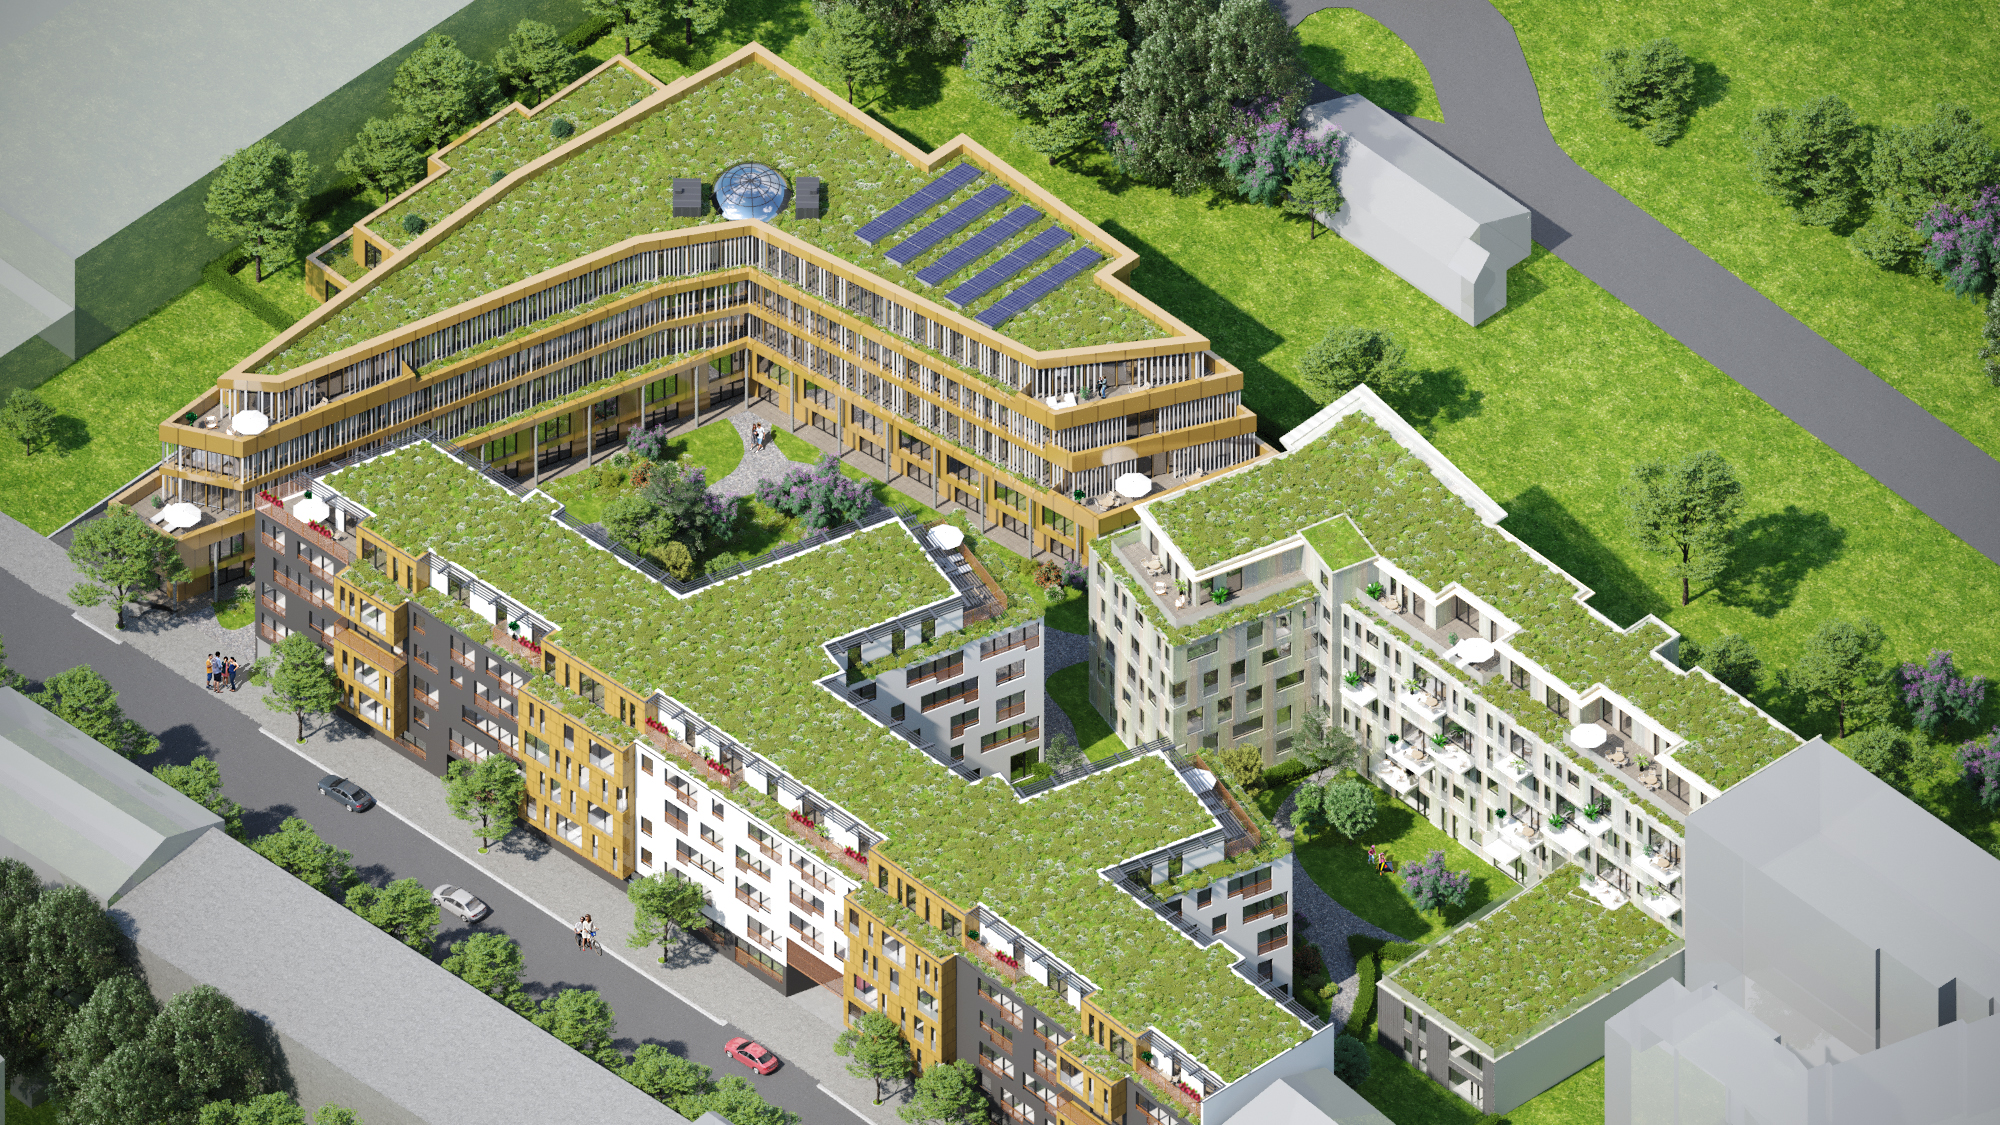
Klärwerkstraße 1 / 1A

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Klärwerkstraße 1 / 1A

Actual purchase price on request

Open presentation ↗

Project link ↗

Commercial development potential based on a 2020 study; railway-purpose release and contaminated-land investigations remain unresolved.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-27.41 %-27,762,387 €
Base-3.55 %-3,188,355 €
Upside10.92 %9,370,202 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost89,699,284 €
Net exit proceeds86,510,928 €
Project profit / loss-3,188,355 €
ROI over the whole project-3.55 %
Illustrative annualized return-0.72 %
Gross proceeds needed to break even92,473,488 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Uses only Real Case 31,852.33 m² BGF, not the larger theoretical concepts. Hard costs: BGF × €1,900/m². Assumed saleable floor area: 80% of BGF × €3,500/m². Neither the efficiency ratio nor exit price is verified.
  • €4m extra-works allowance for investigations, remediation/site preparation and connections is hypothetical and may be exceeded.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
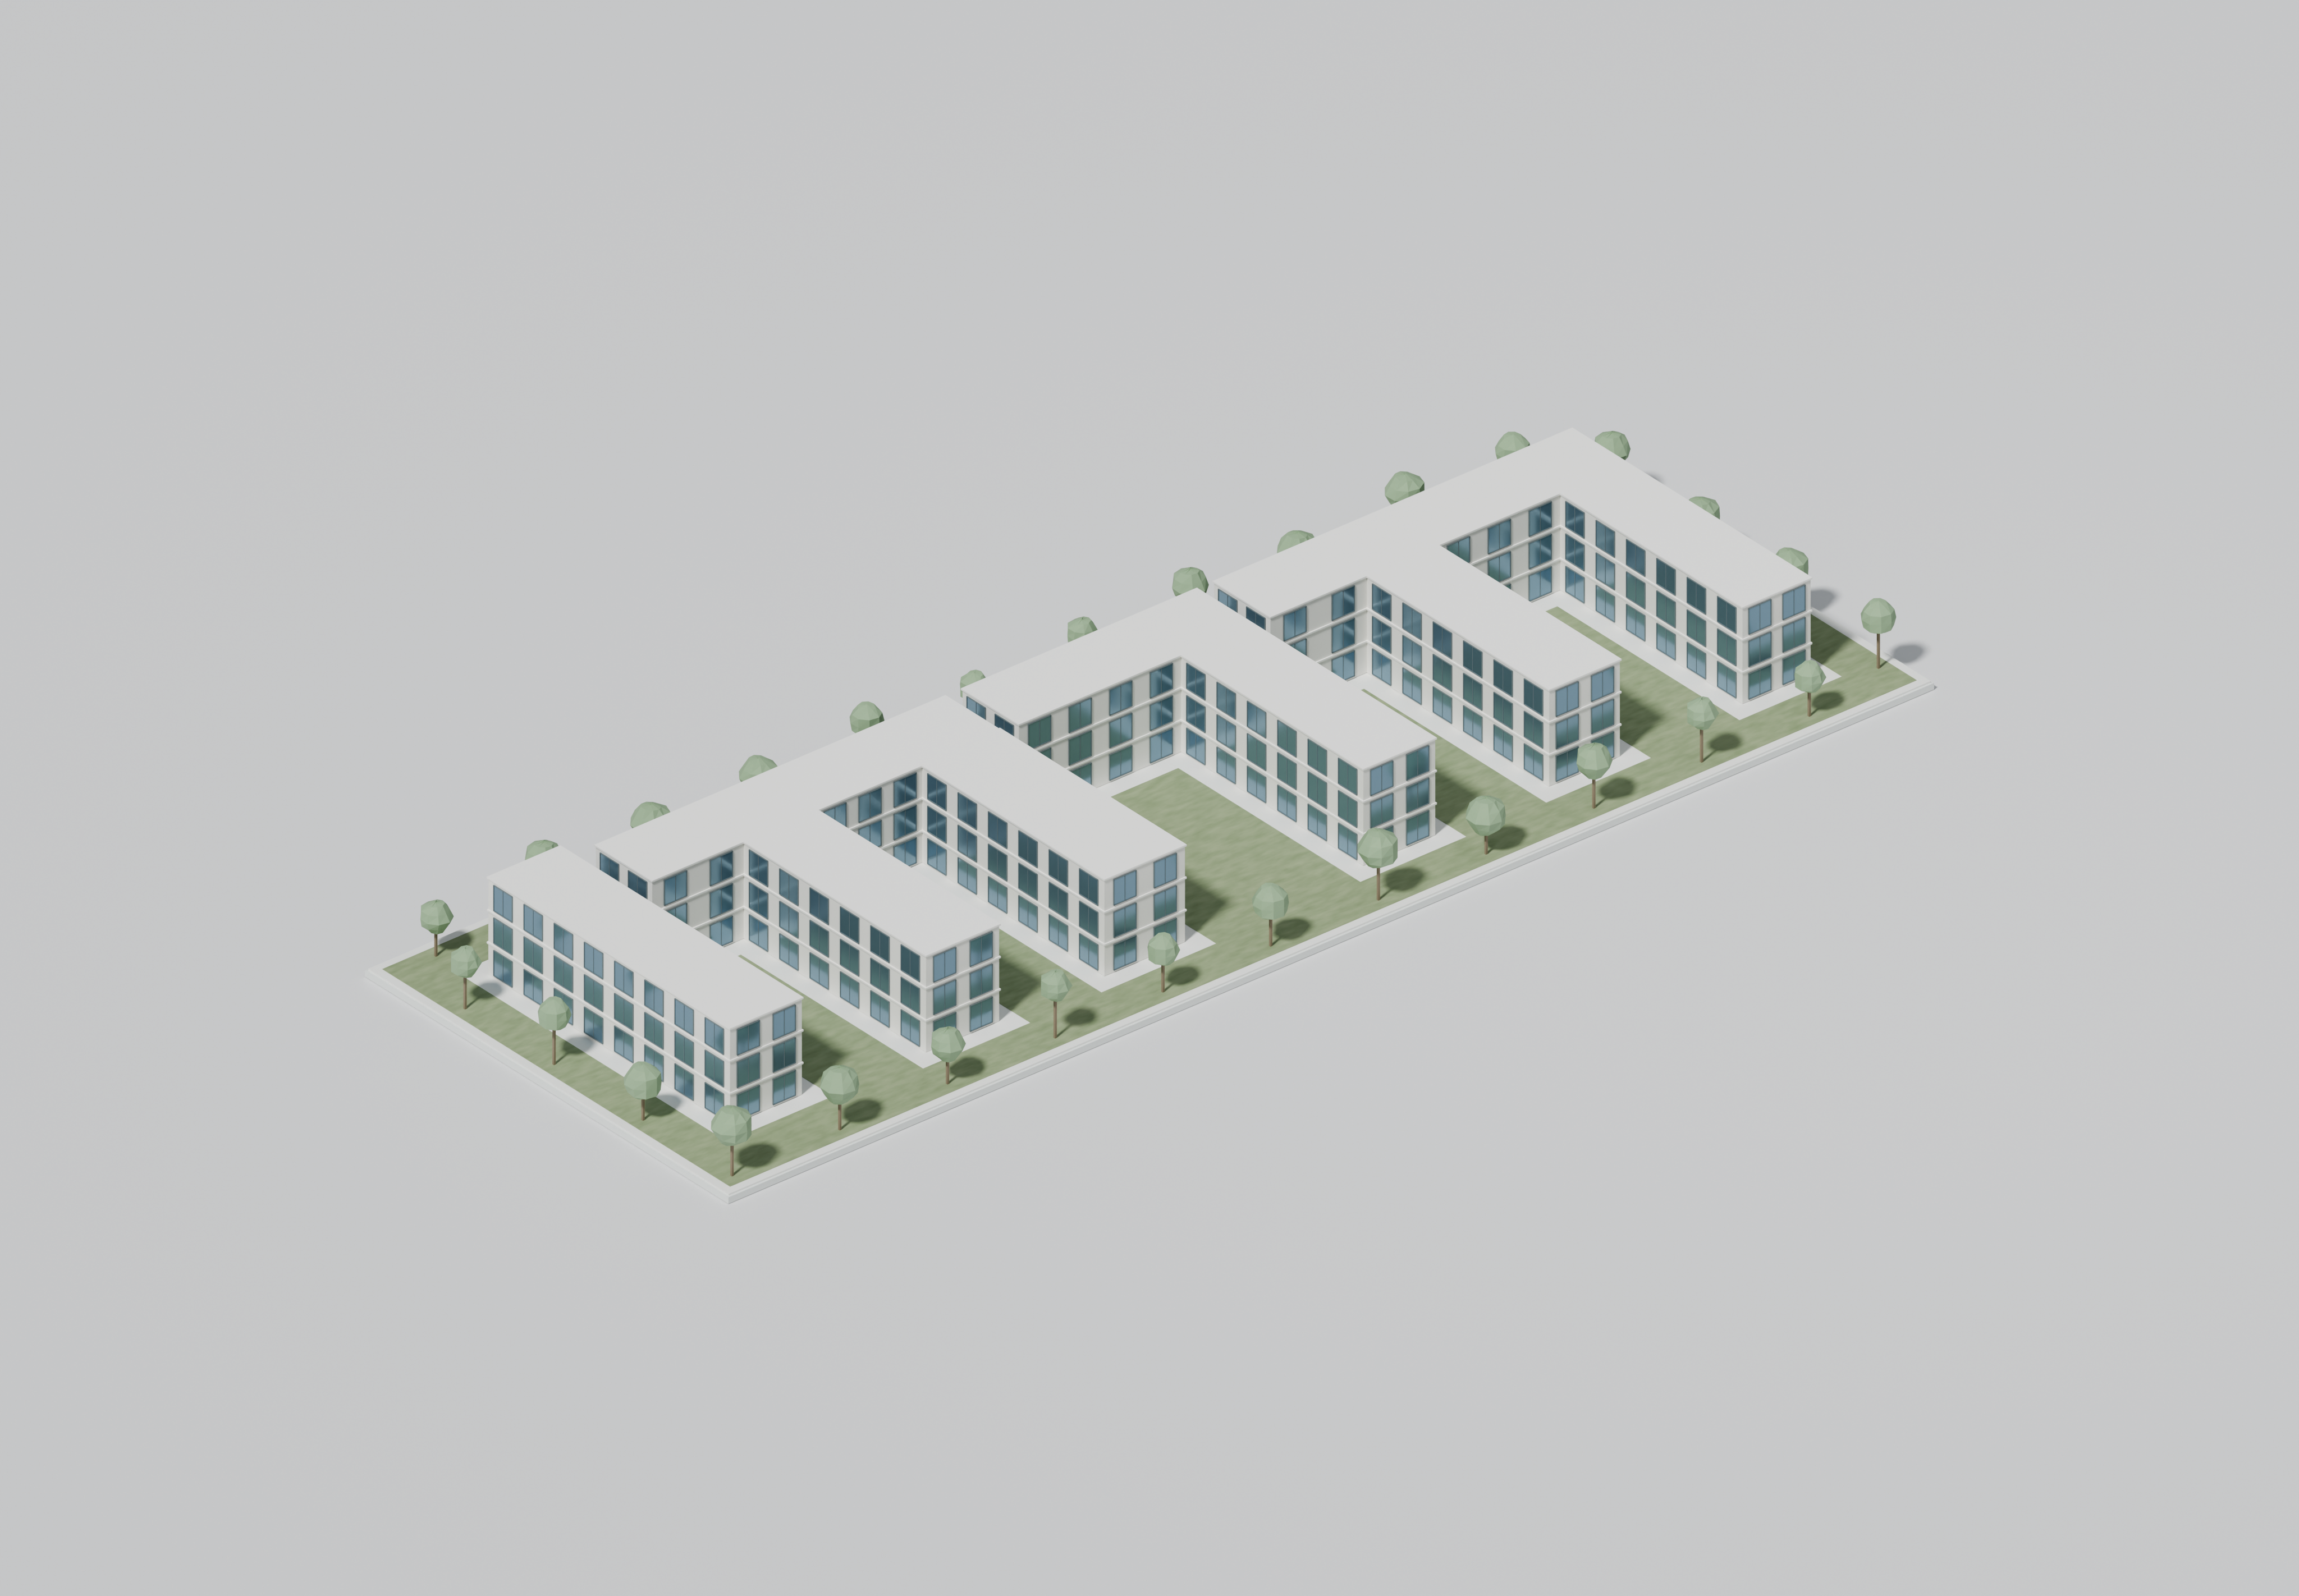
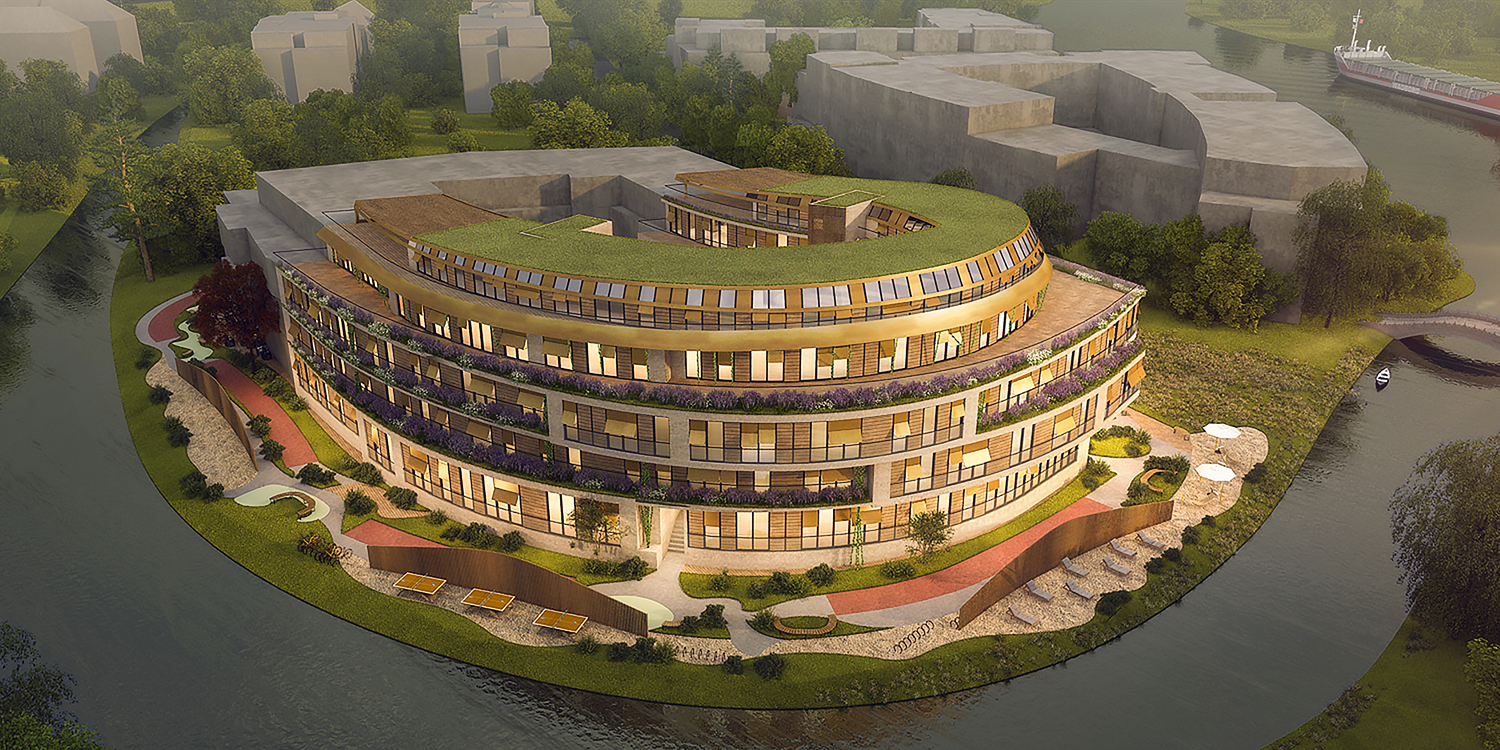
Liebermannstraße 27–37

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Liebermannstraße 27–37

Actual purchase price on request

Open presentation ↗

Project link ↗

Mixed-use development: 70 apartments, 39 new plus 2 existing commercial units and 95 underground parking spaces in the 2022 permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-25.27 %-28,182,807 €
Base-0.15 %-152,059 €
Upside15.10 %14,152,013 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost98,195,188 €
Net exit proceeds98,043,128 €
Project profit / loss-152,059 €
ROI over the whole project-0.15 %
Illustrative annualized return-0.04 %
Gross proceeds needed to break even101,232,152 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: total BGF 27,678.46 m² × €2,500/m²; an illustrative blended rate, not a DIN 276 estimate.
  • Exit: residential 8,019.24 m² × €8,000 + commercial 11,515.49 m² × €3,000 + 95 parking spaces × €25,000. Index I areas include credited balcony shares. All exit rates are assumed. Current permit validity and final saleable areas need confirmation.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
Spandauer Burgwall 46 / 48 / 50

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Spandauer Burgwall 46 / 48 / 50

Actual purchase price on request

Open presentation ↗

Project link ↗

A commercial temporary-accommodation concept with 123 units in two phases; these are not confirmed permanent residential apartments.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-28.37 %-12,049,302 €
Base-4.38 %-1,638,610 €
Upside10.22 %3,651,271 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost37,431,610 €
Net exit proceeds35,793,000 €
Project profit / loss-1,638,610 €
ROI over the whole project-4.38 %
Illustrative annualized return-1.11 %
Gross proceeds needed to break even38,589,289 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: enclosed BGF A 10,803.87 m² × €2,400/m². Hypothetical whole-project exit: 123 × €300,000 = €36.9m, not approved individual apartment sales.
  • No confirmed operator or purchaser, no capitalized invented rent. The €1m extra allowance is not a flood-protection, basement or fit-out estimate.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR. Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

External context: IBB citywide new-build asking-price median, not a valuation of these projects; Berlin tax authority: 6% transfer tax. Other prices and budgets are independent illustrative assumptions. IBB 2025 · Berlin · Grunderwerbsteuer

املاک سرمایه‌گذاری فعلی

املاک برای سرمایه‌گذاری شما

املاکی که اطلاعات اجاره دارند ابتدا نمایش داده می‌شوند. منبع این اطلاعات در کارت هر ملک آمده است.

بازده ناخالص اجاره = اجاره سالانه بدون هزینه‌های جانبی ÷ قیمت خرید. پیش از هزینه‌های خرید و نگهداری، تأمین مالی و مالیات. ·

مستقیم به محاسبه‌گر ↓

ملک شما. محاسبه شما.

جزئیات ملک را بررسی و سناریوی تأمین مالی خود را تنظیم کنید.

یورو · محاسبه ماهانه
اطلاعات ملک

خرید یک ساختمان مسکونی و تجاری 12 اتاقه پر بازده در راینو

قیمت خرید—
مساحت مسکونی—
وضعیت اجاره—
رده انرژی—
اجاره بدون هزینه‌های جانبی / ماه—
بازده ناخالص اجاره—

آنچه باید درباره این ملک بدانید

نتیجه ماهانه شما

در ماه چقدر باقی می‌ماند؟

فرض‌های مدل قابل ویرایش‌اند. این پیشنهاد تأمین مالی نیست.

هنوز اعداد خودتان را ندارید؟

تنظیم وام و سایر فرض‌ها +

آورده شخصی شامل هزینه‌های جانبی خرید است. هزینه‌های مالک شامل هزینه‌های غیرقابل انتقال به مستأجر و ذخیره جاری شماست. تمام درصدها فرض‌های انتخابی هستند.

این مبلغ هر ماه برایتان می‌ماند — پیش از مالیات—

اجاره مبنای محاسبه—
هزینه‌های جاری شما—
قسط وام شما—
نمایش بازده به درصد +

بازده، اجاره سالانه را با قیمت خرید مقایسه می‌کند. این همان پولی نیست که پس از پرداخت قسط وام برایتان می‌ماند.

بازده ناخالص اجاره—
بازده خالص پیش از تأمین مالی¹—
اگر اجاره کمتر یا بهره بیشتر شود چه می‌شود؟ +

¹ اجاره سالانه پس از فرض کاهش وصول، منهای هزینه‌های مالک، تقسیم بر قیمت خرید با احتساب هزینه‌های جانبی. بدون مالیات، افزایش ارزش، بازسازی یک‌باره و هزینه‌های فروش. قسط وام بر مبنای پرداخت سالانه اولیه محاسبه می‌شود؛ این برنامه بازپرداخت نیست.

در ۳۰ ثانیه بفهمید

یک ملک اجاره‌ای چگونه کار می‌کند؟

اینجا یک ملک کامل را برای اجاره دادن می‌خرید. از طریق این وب‌سایت پولی سرمایه‌گذاری نمی‌کنید.

1

یک ملک می‌خرید.

با پول خودتان و در صورت نیاز با وام پرداخت می‌کنید. هزینه‌های جانبی خرید به قیمت ملک اضافه می‌شوند.

2

اجاره دریافت می‌کنید.

اجاره خالص، بدون گرمایش و هزینه‌های بهره‌برداری را مبنا قرار دهید. مبالغ دریافتی بابت گرمایش و هزینه‌های بهره‌برداری، درآمد آزاد شما نیستند.

3

هزینه‌ها را می‌پردازید.

قسط وام و هزینه‌های جاری خودتان کسر می‌شوند. آنچه باقی می‌ماند را در محاسبه‌گر می‌بینید.

اجاره پس از فرض کاهش وصول−هزینه‌های جاری شما−قسط وام=مبلغ باقی‌مانده ماهانه
روندی اصولی. بدون میان‌بُر.

از اسناد تا تصمیمی روشن.

01

تصویر کامل را ببینید.

معرفی ملک، قرارداد اجاره، بودجه سالانه ساختمان و وضعیت ملک در کنار هم تصویر کاملی می‌سازند.

02

با جزئیات محاسبه کنید.

اجاره، تأمین مالی و هزینه‌های جاری. بر اساس فرض‌های شما و با نگاهی به ریسک‌ها.

03

در گفت‌وگوی شخصی روشن کنید.

پیش از برداشتن گام بعدی، پرسش‌های باز و شرایط را بررسی کنید.

پرسش‌های خوب، پاسخ‌های ساده

آنچه پیش از خرید باید فهمیده باشید.

آیا «اجاره» خودبه‌خود به معنی «سود» است؟

خیر. هزینه‌های جاری و در صورت وجود قسط وام از اجاره کسر می‌شوند. محاسبه‌گر نشان می‌دهد پس از آن، پیش از مالیات چه می‌ماند.

منفی بودن نتیجه یعنی چه؟

در این محاسبه، اجاره واردشده همه هزینه‌ها را پوشش نمی‌دهد. باید هر ماه مبلغ نمایش‌داده‌شده را از منابع مالی دیگر بپردازید.

چرا بعضی فیلدها خالی‌اند؟

برای این ملک هنوز اطلاعات بررسی‌شده موجود نیست. مبلغ اجاره را از خودمان نمی‌سازیم. مقادیر معلوم را وارد کنید یا اسناد را با ما بررسی کنید.

آیا می‌توانم به نتیجه تکیه کنم؟

این یک محاسبه مدل‌سازی‌شده با ورودی‌های شماست، نه تعهد. اجاره کمتر، تعمیرات یا شرایط متفاوت وام، نتیجه را تغییر می‌دهند. مالیات، بازسازی‌های یک‌باره و هزینه‌های فروش محاسبه نشده‌اند.

وقتی درخواست می‌فرستم چه می‌شود؟

اورپیک اطلاعات تماس، ملک انتخاب‌شده و محاسبه شما را دریافت می‌کند. سپس می‌توانیم موارد باز را با شما بررسی کنیم. ارسال درخواست به معنی خرید ملک نیست.

EVERPEAK PRIVATE

از ۱ میلیون یورو. سرمایه شما. چشم‌انداز شما.

گفت‌وگو درباره سرمایه‌گذاری خصوصی ↗
5,0 ★★★★★

33 نظرات در گوگل

«ارتباط و خدمات عالی. پاول پاسخگو، خوش برخورد و حرفه ای واقعی است.» — Angela

«او در کنار مشتری است و از منافع آنها دفاع می کند - امری نادر در برلین! بسیار توصیه می شود.» — Artem S.

«هر بار نتیجه حتی بهتر از چیزی بود که برنامه ریزی کرده بودیم.» — Natalia H.

ترجمه از روسی

همه نظرات را در Google بخوانید

گام بعدی

پرسش‌های شما. نگاه مشترک ما.

درباره ملک و سناریوی محاسباتی شما گفت‌وگو می‌کنیم.
شخصی، مشخص و بدون تعهد.

با ارسال درخواست، اطلاعات تماس و سناریوی محاسباتی فعلی خود را برای اورپیک می‌فرستید. اطلاعات حریم خصوصی