Everpeak Properties
NieruchomościKalkulator inwestycjiIndywidualne doradztwo · od 1 mln €
EVERPEAK INVESTMENT

Nieruchomości inwestycyjne.

Porównaj ceny zakupu, dostępne dane o czynszu i rentowność brutto. Poznaj nieruchomość i oblicz swój miesięczny wynik.

EVERPEAK · DEVELOPMENT

Development projects

Five projects with reviewed source documents and separate scenario economics. Actual purchase prices are on request. All purchase prices, budgets and exit values below are illustrative assumptions.

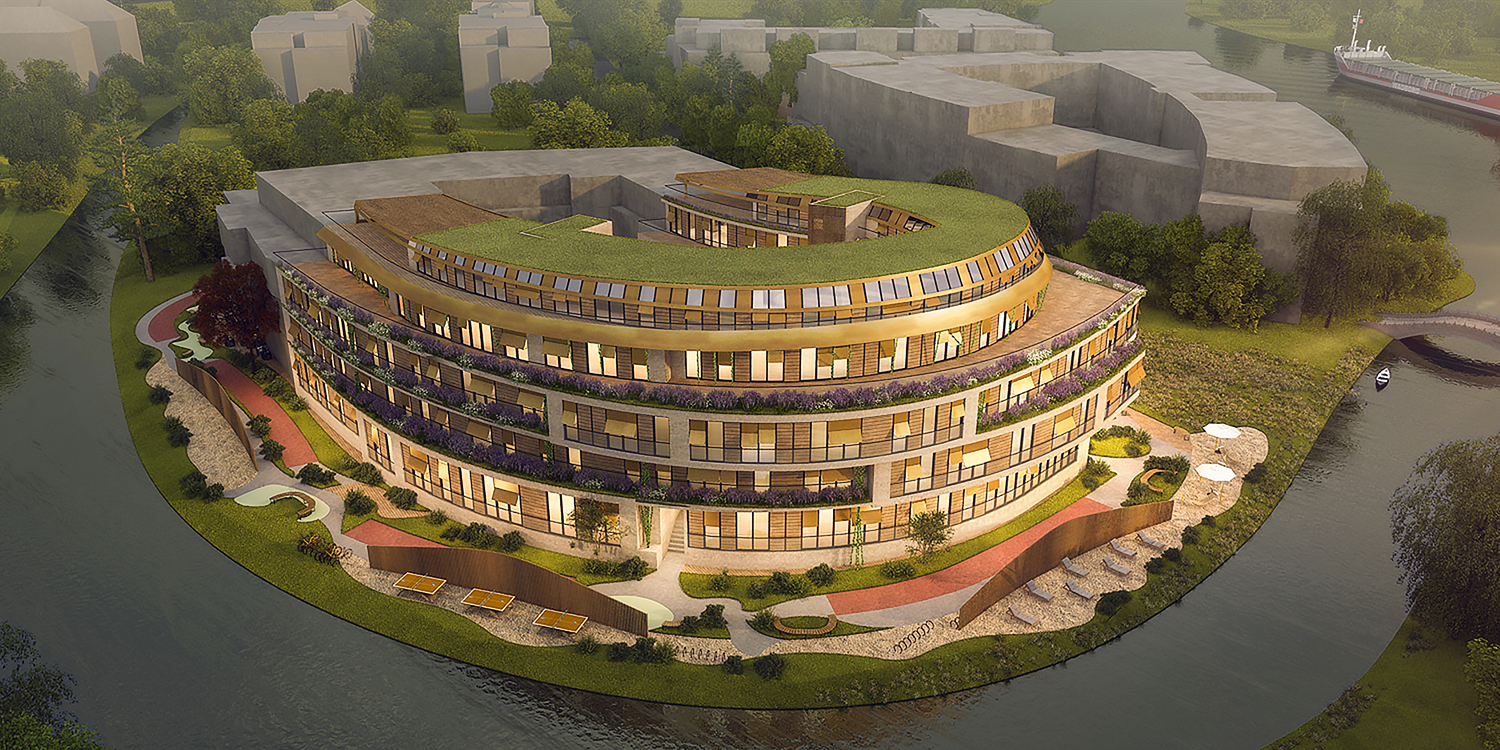
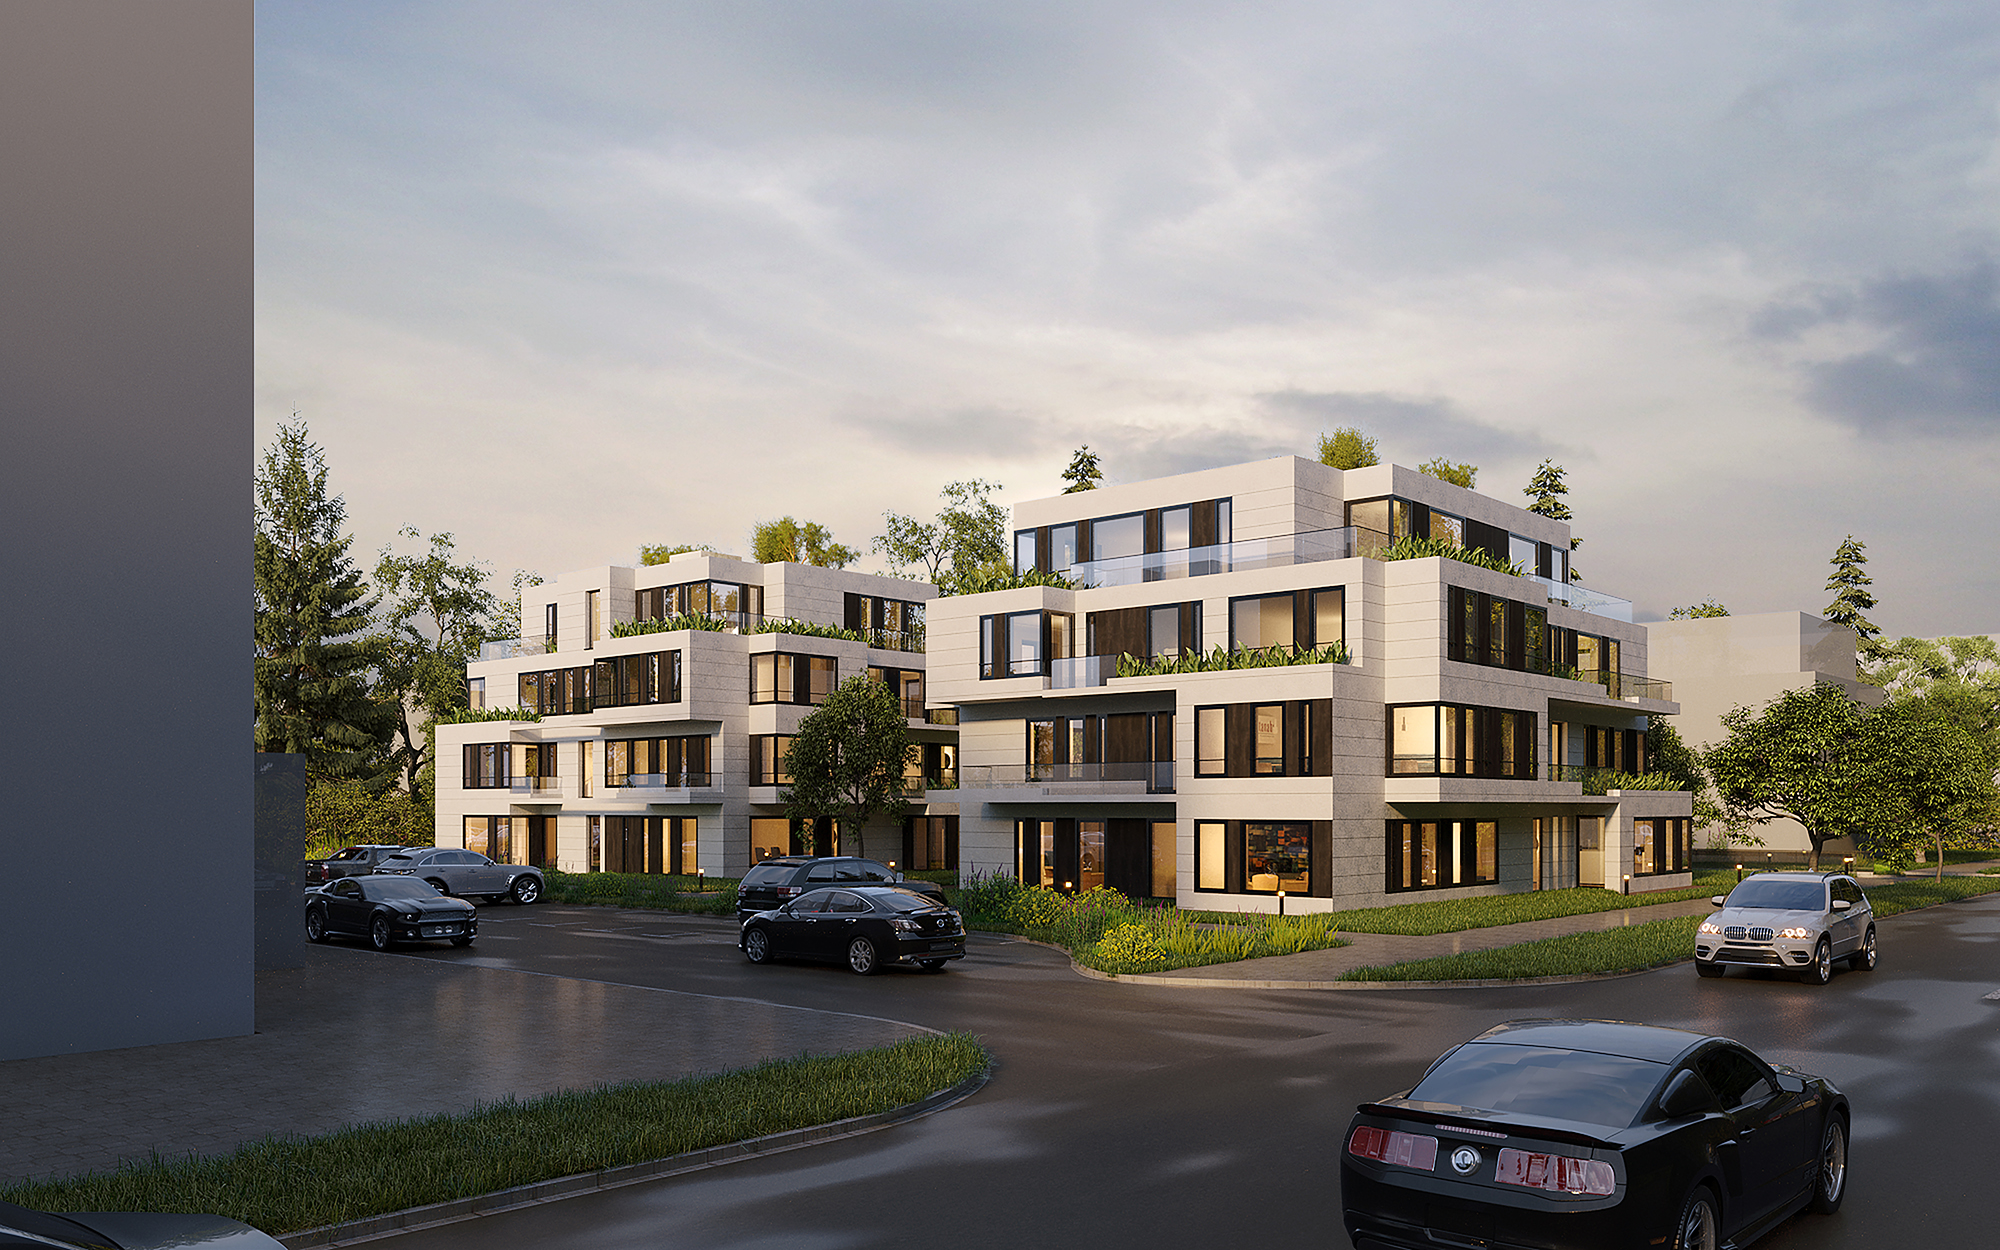
Spandauer Burgwall 46 / 48 / 50

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Spandauer Burgwall 46 / 48 / 50

Actual purchase price on request

Open presentation ↗

Project link ↗

A commercial temporary-accommodation concept with 123 units in two phases; these are not confirmed permanent residential apartments.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-28.37 %-12,049,302 €
Base-4.38 %-1,638,610 €
Upside10.22 %3,651,271 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost37,431,610 €
Net exit proceeds35,793,000 €
Project profit / loss-1,638,610 €
ROI over the whole project-4.38 %
Illustrative annualized return-1.11 %
Gross proceeds needed to break even38,589,289 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: enclosed BGF A 10,803.87 m² × €2,400/m². Hypothetical whole-project exit: 123 × €300,000 = €36.9m, not approved individual apartment sales.
  • No confirmed operator or purchaser, no capitalized invented rent. The €1m extra allowance is not a flood-protection, basement or fit-out estimate.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
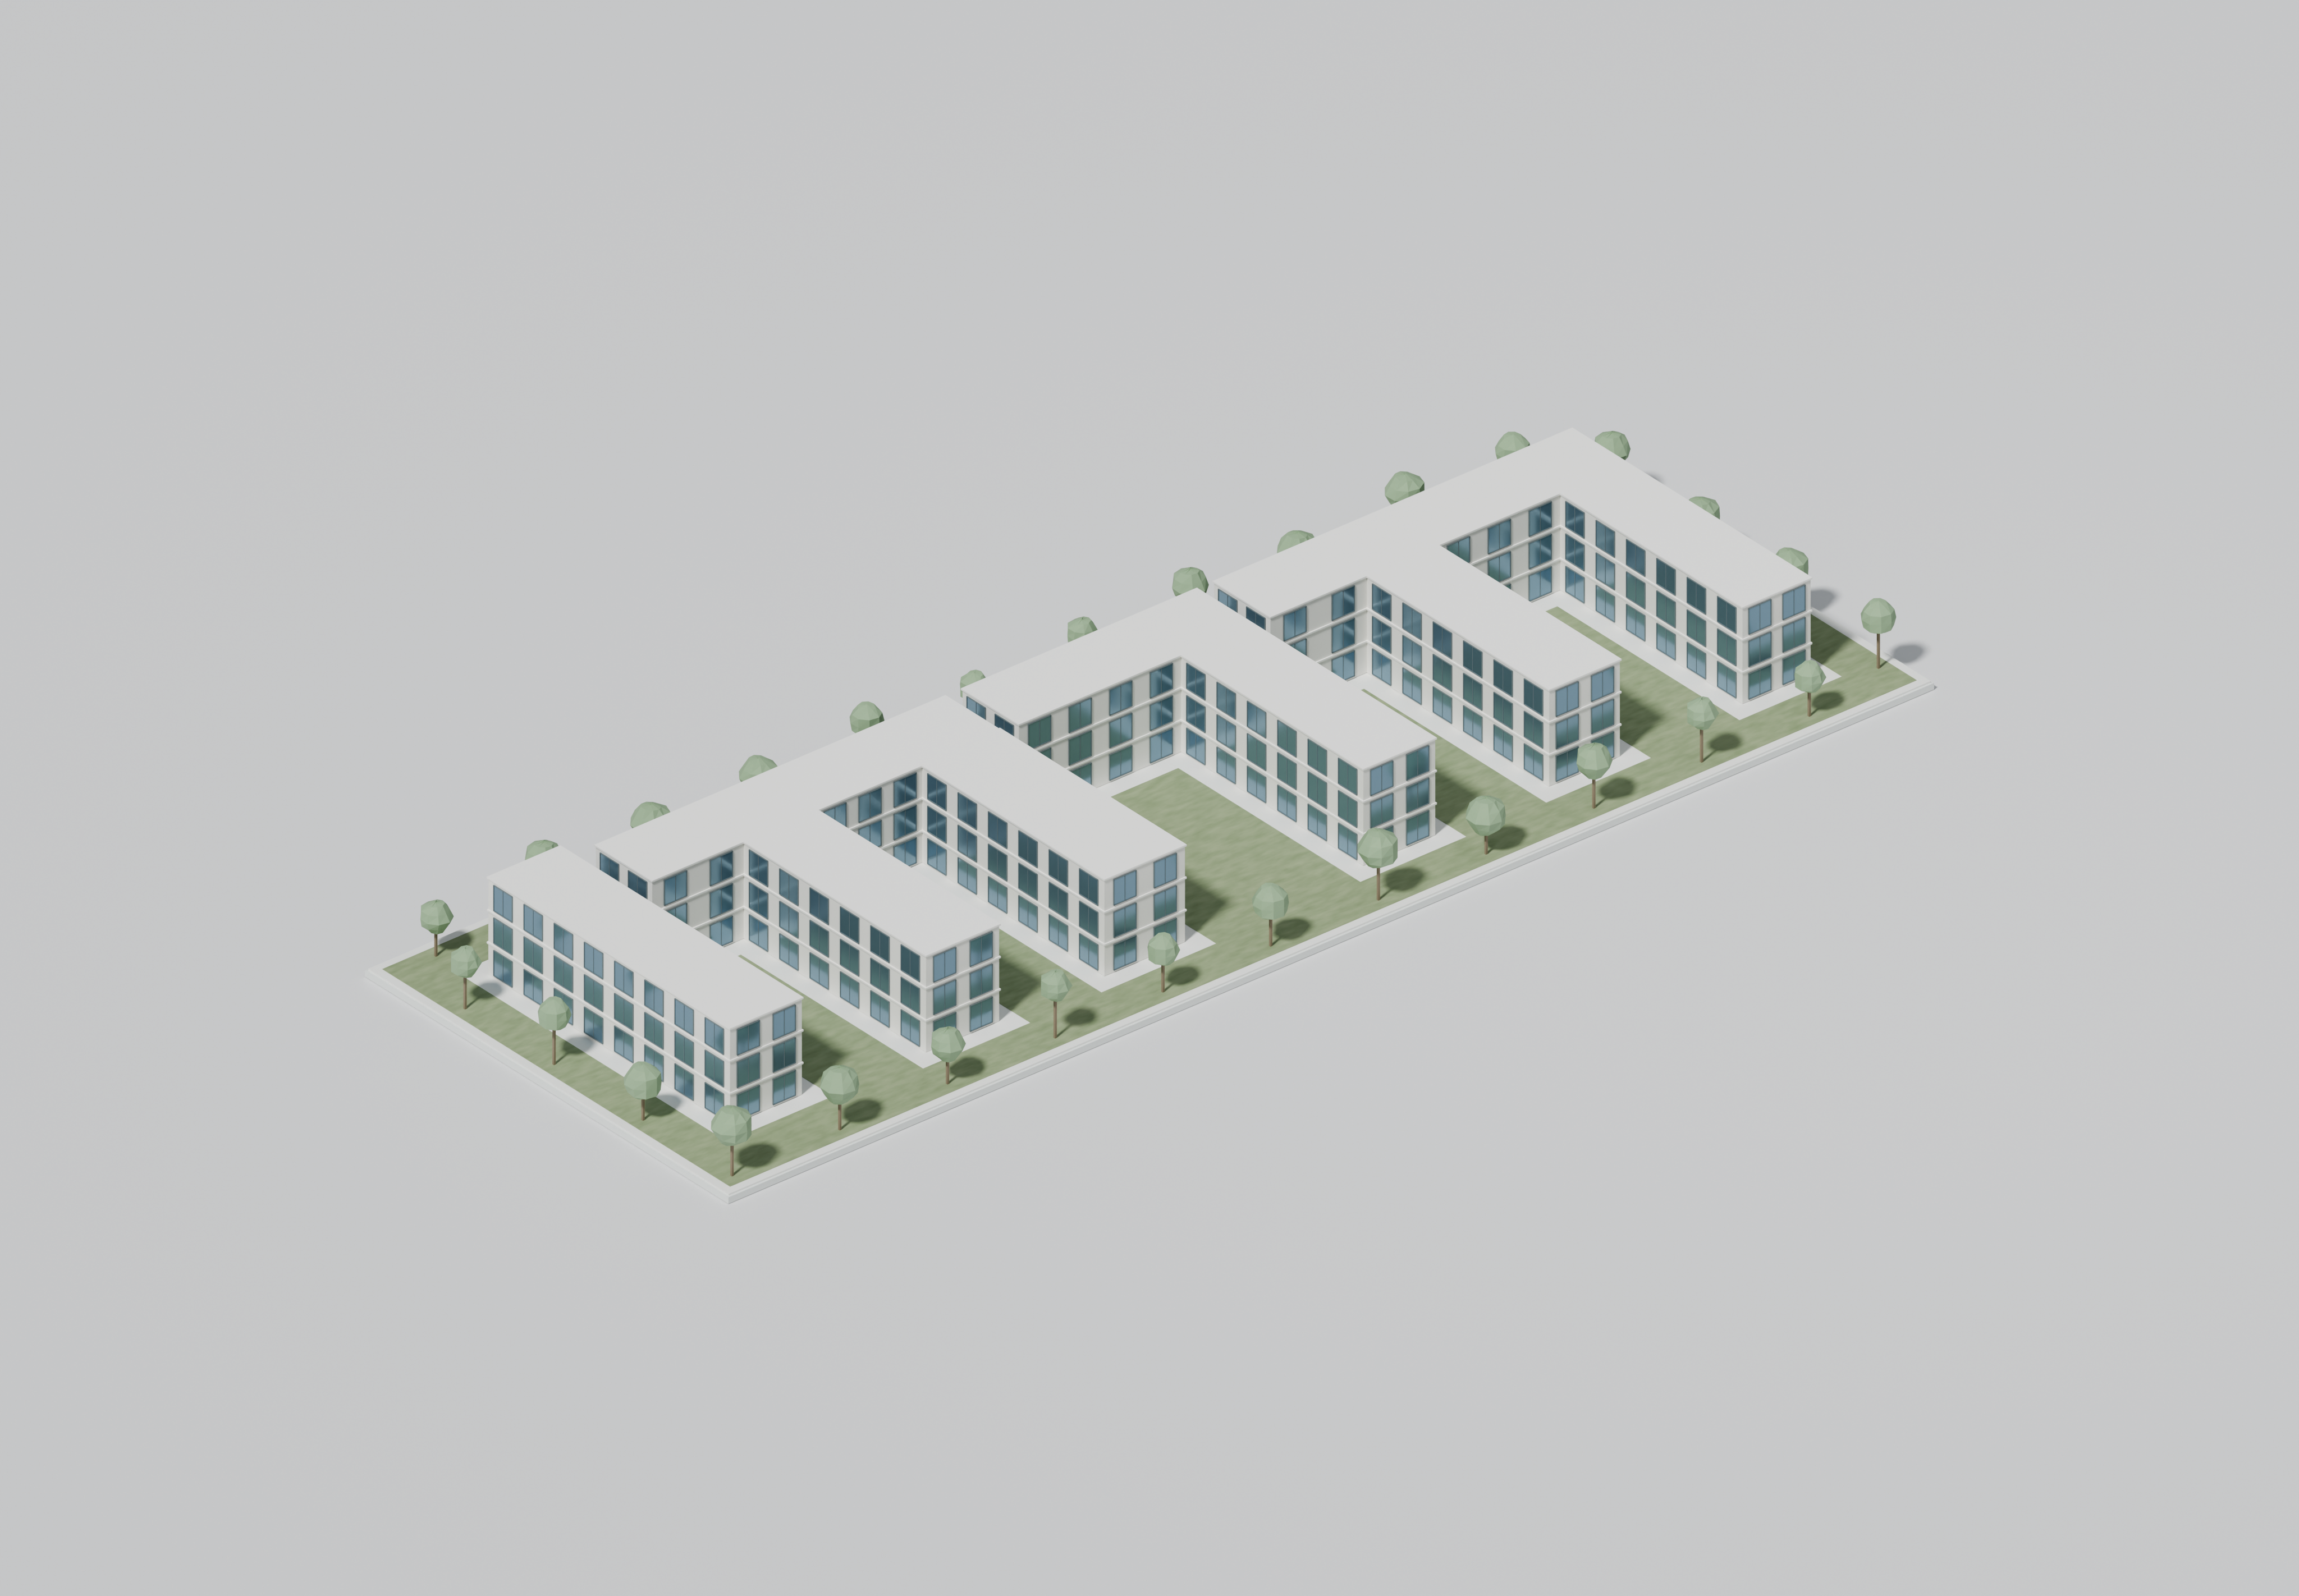
Asta-Nielsen-Straße 4

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Asta-Nielsen-Straße 4

Actual purchase price on request

Open presentation ↗

Project link ↗

Three planned residential buildings with 39 apartments in a June 2026 preliminary application, not an issued building permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-7.38 %-1,182,406 €
Base20.70 %2,993,995 €
Upside37.87 %5,275,795 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost14,466,005 €
Net exit proceeds17,460,000 €
Project profit / loss2,993,995 €
ROI over the whole project20.70 %
Illustrative annualized return6.47 %
Gross proceeds needed to break even14,913,407 €
Maximum purchase price at target ROI3,576,359 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: 2,989.54 m² BGF × €2,600/m². Assumed saleable residential area: 2,400 m² × €7,500/m², not verified Wohnfläche.
  • Netto 2,600.53 m², stated rentable area 2,914.24 m² and BGF are different measures. The 55.71/74.35 m² first-floor discrepancy and upper-floor classification remain unresolved.
  • Existing-building energy class G and 237.1 kWh/(m²a) do not apply to the new development. No parking sales or existing rental income are included.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
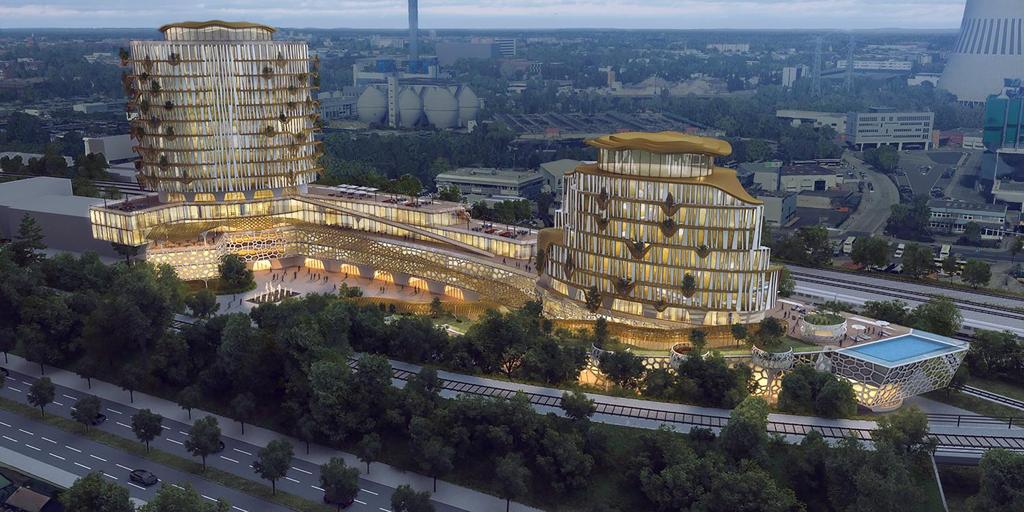
Klärwerkstraße 1 / 1A

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Klärwerkstraße 1 / 1A

Actual purchase price on request

Open presentation ↗

Project link ↗

Commercial development potential based on a 2020 study; railway-purpose release and contaminated-land investigations remain unresolved.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-27.41 %-27,762,387 €
Base-3.55 %-3,188,355 €
Upside10.92 %9,370,202 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost89,699,284 €
Net exit proceeds86,510,928 €
Project profit / loss-3,188,355 €
ROI over the whole project-3.55 %
Illustrative annualized return-0.72 %
Gross proceeds needed to break even92,473,488 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Uses only Real Case 31,852.33 m² BGF, not the larger theoretical concepts. Hard costs: BGF × €1,900/m². Assumed saleable floor area: 80% of BGF × €3,500/m². Neither the efficiency ratio nor exit price is verified.
  • €4m extra-works allowance for investigations, remediation/site preparation and connections is hypothetical and may be exceeded.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
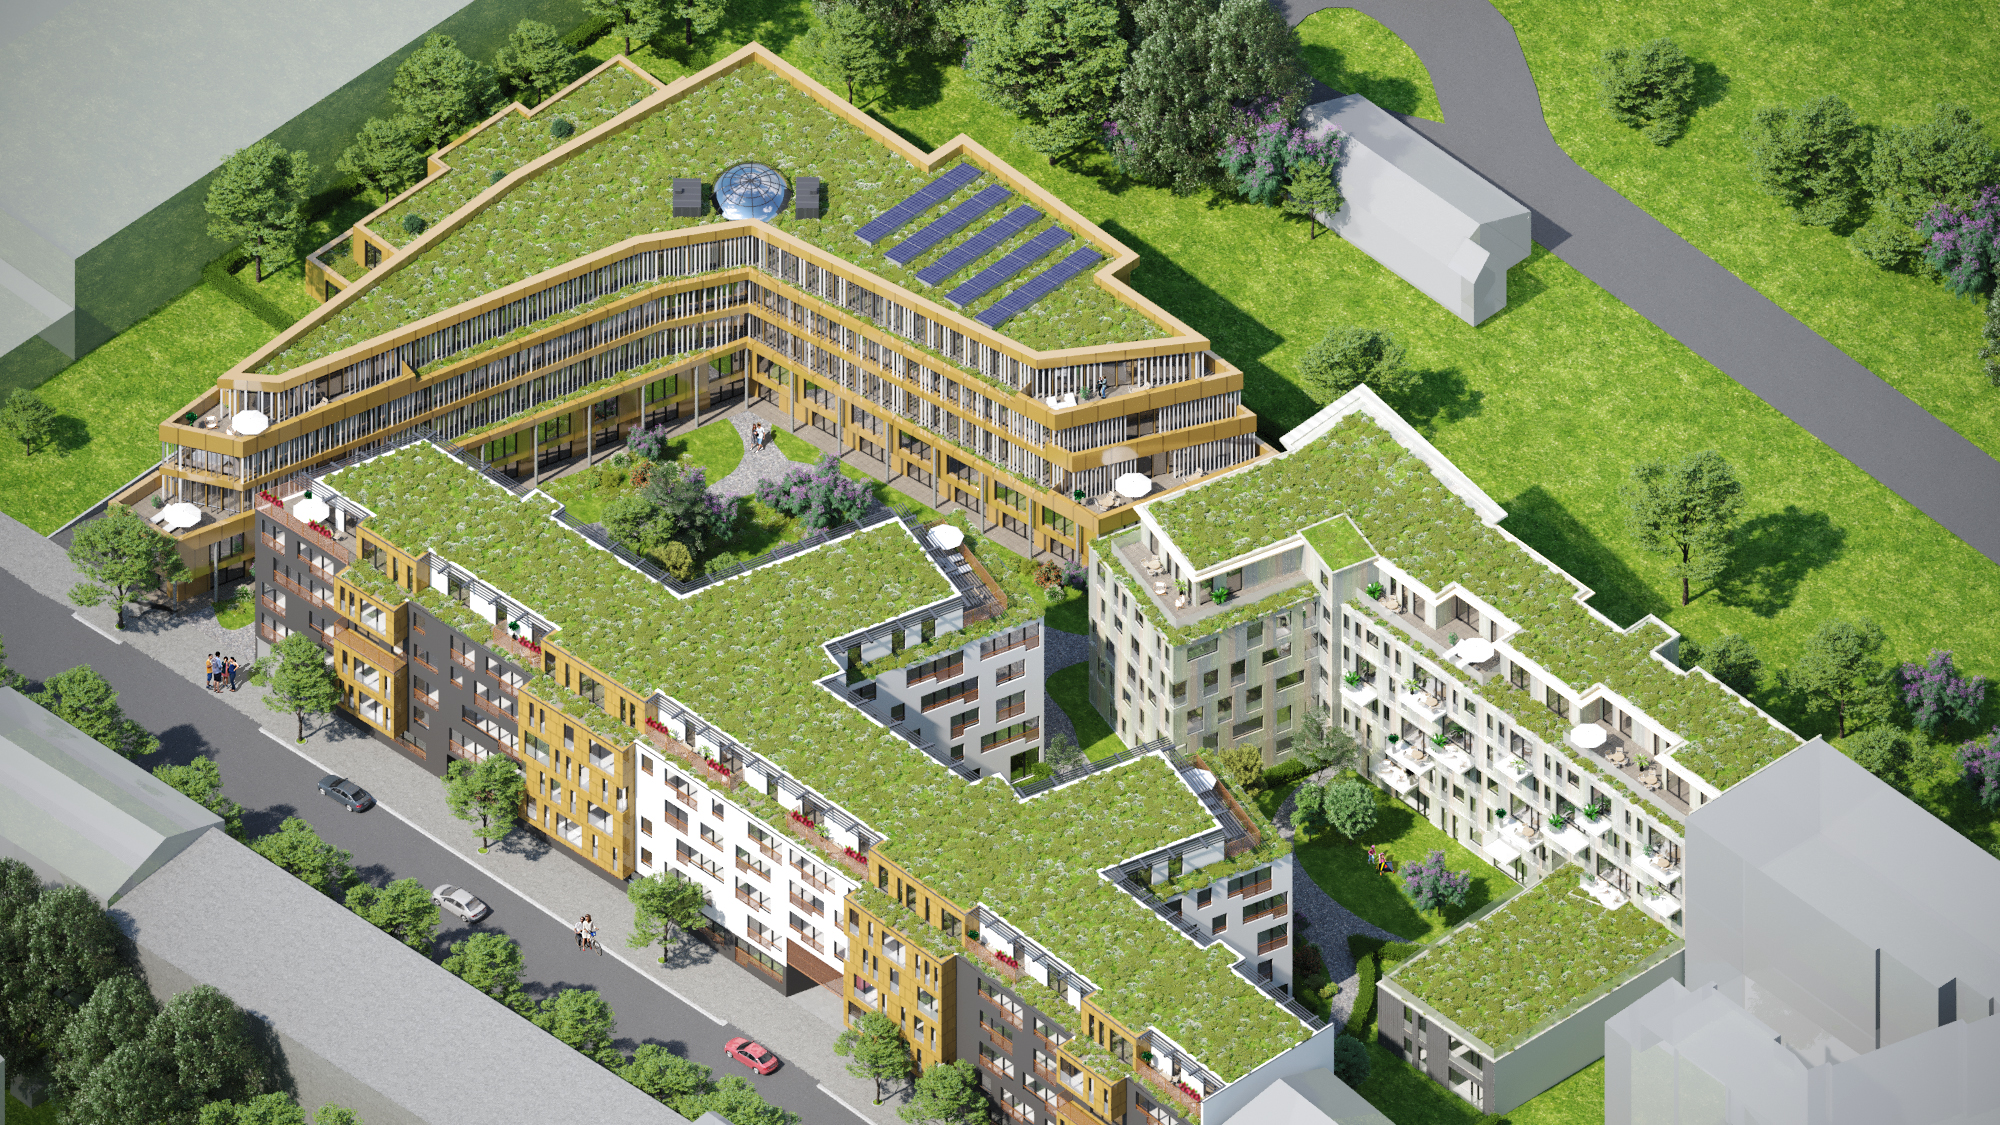
Liebermannstraße 27–37

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Liebermannstraße 27–37

Actual purchase price on request

Open presentation ↗

Project link ↗

Mixed-use development: 70 apartments, 39 new plus 2 existing commercial units and 95 underground parking spaces in the 2022 permit.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-25.27 %-28,182,807 €
Base-0.15 %-152,059 €
Upside15.10 %14,152,013 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost98,195,188 €
Net exit proceeds98,043,128 €
Project profit / loss-152,059 €
ROI over the whole project-0.15 %
Illustrative annualized return-0.04 %
Gross proceeds needed to break even101,232,152 €
Maximum purchase price at target ROINo positive purchase price achieves the target ROI under these assumptions.

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs: total BGF 27,678.46 m² × €2,500/m²; an illustrative blended rate, not a DIN 276 estimate.
  • Exit: residential 8,019.24 m² × €8,000 + commercial 11,515.49 m² × €3,000 + 95 parking spaces × €25,000. Index I areas include credited balcony shares. All exit rates are assumed. Current permit validity and final saleable areas need confirmation.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗
Wilhelm-von-Siemens-Straße 32

Project visualization, not a photograph of a completed building.

ILLUSTRATIVE SCENARIO · NOT A RETURN FORECAST

Wilhelm-von-Siemens-Straße 32

Actual purchase price on request

Open presentation ↗

Project link ↗

The February 2026 student-housing concept is separate from the older medical-use preliminary decision.

Source documents reviewed; current planning status requires confirmation.

ROI over the whole project
ScenarioROIProject profit / loss
Downside-14.08 %-4,232,174 €
Base13.82 %3,688,545 €
Upside30.83 %7,872,368 €
Edit assumptions and recalculate

Model inputs, not seller terms

Purchase costs 10%: 6% transfer tax, assumed 2% notary/register and 2% brokerage; design 15% and contingency 10% of hard costs; selling costs 3%. Inputs are editable. This is not a cost estimate, market valuation or assurance of sale or planning approval.

Total project cost26,683,125 €
Net exit proceeds30,371,670 €
Project profit / loss3,688,545 €
ROI over the whole project13.82 %
Illustrative annualized return3.29 %
Gross proceeds needed to break even27,508,376 €
Maximum purchase price at target ROI2,251,455 €

ROI = (sale proceeds after selling costs − total project cost) / total project cost. Total cost includes acquisition, purchase costs, construction, design, contingency, extra works and holding costs over the project period.

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR.

Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

Basis and assumptions

  • Hard costs use 7,455 m² of GFZ calculation area × €2,300/m² as a preliminary proxy, not confirmed BGF. Model exit: 70% of 7,455 m² × €6,000/m².
  • Area efficiency, prices, residential use and saleability are assumptions. No confirmed apartment count or transferred approval from the medical scheme.

Verify before acquisition

  • Actual acquisition price, current planning consent, saleable floor area, costs and exit proceeds require independent confirmation.
  • All model returns are hypothetical and may be negative.
Discuss this project ↗

Unlevered, before income taxes. Construction budgets assume VAT included; no VAT recovery is modelled. No rental income. Annualized = (net exit / total cost)^(1/years) − 1 assuming all costs occur at the start; this is not cash-flow IRR. Downside: hard costs +15%, exit −15%, duration +1 year. Upside: hard costs −5%, exit +10%, duration −0.5 year. Purchase and other rates remain unchanged.

External context: IBB citywide new-build asking-price median, not a valuation of these projects; Berlin tax authority: 6% transfer tax. Other prices and budgets are independent illustrative assumptions. IBB 2025 · Berlin · Grunderwerbsteuer

AKTUALNE NIERUCHOMOŚCI INWESTYCYJNE

Nieruchomości dla Twojej inwestycji

Najpierw wyświetlamy nieruchomości z danymi o czynszu. Każda karta podaje źródło tych danych.

Rentowność najmu brutto = roczny czynsz bez opłat ÷ cena zakupu. Przed kosztami nabycia i utrzymania, finansowaniem i podatkami. ·

Przejdź prosto do kalkulatora ↓

Twoja nieruchomość. Twoje obliczenia.

Sprawdź szczegóły nieruchomości i dostosuj własny scenariusz finansowania.

EUR · ujęcie miesięczne
Dane nieruchomości

Kup wysokodochodowy 12-pokojowy budynek mieszkalno-usługowy w Rhinow

Cena zakupu—
Powierzchnia mieszkalna—
Status najmu—
Klasa energetyczna—
Czynsz bez opłat / miesiąc—
Rentowność najmu brutto—

Co warto wiedzieć o tej nieruchomości

TWÓJ MIESIĘCZNY WYNIK

Ile zostaje co miesiąc?

Edytowalne założenia modelu. To nie jest oferta finansowania.

Nie masz jeszcze własnych danych?

Dostosuj kredyt i pozostałe założenia +

Kapitał własny obejmuje dodatkowe koszty nabycia. Koszty właściciela obejmują koszty nieprzenoszone na najemcę i bieżącą rezerwę. Wszystkie wartości procentowe są dowolnie przyjętymi założeniami.

Tyle zostaje Ci co miesiąc — przed podatkami—

Czynsz przyjęty do obliczeń—
Twoje bieżące koszty—
Twoja rata kredytu—
Zobacz rentowność w procentach +

Rentowność porównuje roczny czynsz z ceną zakupu. Nie jest to kwota pozostająca po spłacie raty kredytu.

Rentowność najmu brutto—
Rentowność netto przed finansowaniem¹—
Co się stanie przy niższym czynszu lub wyższych odsetkach? +

¹ Roczny czynsz po uwzględnieniu założonej utraty wpływów, pomniejszony o koszty właściciela, podzielony przez cenę zakupu wraz z kosztami nabycia. Bez podatków, wzrostu wartości, jednorazowego remontu i kosztów sprzedaży. Rata kredytu jako początkowa płatność annuitetowa; to nie jest harmonogram spłat.

Omów mój wynik ↗

ZROZUMIESZ W 30 SEKUND

Tak działa nieruchomość na wynajem.

Tutaj kupujesz całą nieruchomość, aby ją wynajmować. Nie inwestujesz pieniędzy za pośrednictwem tej strony.

1

Kupujesz nieruchomość.

Płacisz własnymi środkami i, w razie potrzeby, kredytem. Do ceny zakupu dochodzą dodatkowe koszty nabycia.

2

Otrzymujesz czynsz.

Przyjmij czynsz netto, bez ogrzewania i opłat eksploatacyjnych. Pieniądze na ogrzewanie i eksploatację nie są dochodem do swobodnej dyspozycji.

3

Opłacasz wydatki.

Odliczasz ratę kredytu i własne bieżące koszty. Kalkulator pokazuje to, co pozostaje.

Czynsz po uwzględnieniu założonej utraty wpływów−Twoje bieżące koszty−Rata kredytu=Kwota pozostająca co miesiąc
RZETELNY PROCES. BEZ DROGI NA SKRÓTY.

Od dokumentów do jasnej decyzji.

01

Zobacz całość.

Oferta, umowa najmu, plan gospodarczy i stan nieruchomości razem tworzą pełny obraz.

02

Policz szczegółowo.

Czynsz, finansowanie i bieżące koszty. Z Twoimi założeniami i uwzględnieniem ryzyka.

03

Wyjaśnij osobiście.

Omów otwarte pytania i warunki, zanim podejmiesz kolejny krok.

DOBRE PYTANIA, PROSTE ODPOWIEDZI

Co warto zrozumieć przed zakupem.

Czy „czynsz” automatycznie oznacza „zysk”?

Nie. Od czynszu odlicza się bieżące koszty i ewentualną ratę kredytu. Kalkulator pokazuje, co pozostaje przed podatkami.

Co oznacza ujemny wynik?

W tym obliczeniu podany czynsz nie wystarcza na wszystkie wydatki. Wskazaną kwotę trzeba co miesiąc dopłacać z innych środków.

Dlaczego niektóre pola są puste?

Dla tej nieruchomości nie ma jeszcze sprawdzonych danych. Nie wymyślamy czynszu. Wpisz znane wartości lub wspólnie z nami wyjaśnij dokumentację.

Czy mogę polegać na wyniku?

To obliczenie modelowe na podstawie Twoich danych, a nie obietnica. Niższy czynsz, naprawy lub inne warunki kredytu zmieniają wynik. Podatki, jednorazowe remonty i koszty sprzedaży nie są uwzględnione.

Co się stanie, gdy wyślę zapytanie?

Everpeak otrzyma Twoje dane kontaktowe, wybraną nieruchomość i obliczenia. Możemy wtedy omówić z Tobą otwarte kwestie. Zapytanie nie powoduje zakupu nieruchomości.

EVERPEAK PRIVATE

Od 1 miliona euro. Twój kapitał. Twoja perspektywa.

Porozmawiaj o inwestycji prywatnej ↗
5,0 ★★★★★

33 recenzje w Google

«Doskonała komunikacja i obsługa. Paweł jest responsywny, przystępny i prawdziwy profesjonalista.» — Angela

«Jest po stronie klienta i broni jego interesów – co jest rzadkością w Berlinie! Gorąco polecam.» — Artem S.

«Za każdym razem efekt był jeszcze lepszy niż planowaliśmy.» — Natalia H.

Przetłumaczone z języka rosyjskiego

Przeczytaj wszystkie recenzje w Google

NASTĘPNY KROK

Twoje pytania. Nasze wspólne spojrzenie.

Omówimy nieruchomość i Twój scenariusz obliczeń.
Indywidualnie, konkretnie i bez zobowiązań.

Wysyłając zapytanie, przekazujesz Everpeak swoje dane kontaktowe i aktualny scenariusz obliczeń. Informacje o ochronie danych